What Happens to Your Credit Score If You Close a Bank Account?
Updated: 12 Dec 2025

Written bySingSaver Team
Team
The information on this page is for educational and informational purposes only and should not be considered financial or investment advice. While we review and compare financial products to help you find the best options, we do not provide personalised recommendations or investment advisory services. Always do your own research or consult a licensed financial professional before making any financial decisions.
Closing a bank account can seem daunting, mostly due to worries about negative impacts on your credit score (and the hassle of getting it done). But here, it’s a relatively safe decision due to how Singapore measures your credit score, which is different from other countries.
That said, while closing a bank account won’t appear on your credit report, indirect effects can still happen if the account isn’t handled properly — we’ll explain how that works in the sections below.
It’s never too early to start building your credit score
Establishing a solid credit history now can unlock better loan rates, job opportunities, and financial freedom down the road.
Closing your bank account usually won’t hurt your credit
In most cases, closing a bank account won’t hurt your credit score.
That’s because bank accounts are not included in credit reporting in Singapore. The Credit Bureau Singapore (CBS) tracks data related to your borrowing behaviour — such as loans, credit cards, and payment histories — but not your savings, current, or joint accounts. These types of accounts are not credit products, so they don’t factor into your credit score at all.
Still, there are situations where things can go sideways. So while closing a bank account doesn’t impact your score directly, the way you do it can lead to indirect consequences — especially if your account isn’t properly settled beforehand.
What could go wrong if you don’t close the account properly
Your credit score could drop — not because you closed the account, but because of what you left behind.
If a bank account is closed while still carrying unpaid fees, or if it’s overdrawn due to an active overdraft facility, the bank might escalate the outstanding amount to a debt collection agency. Once that happens, the debt can be reported to CBS and appear on your credit report.
Here are some common ways this might happen in Singapore:
-
You forget to cancel GIRO payments to telcos or utility providers, and a charge bounces after account closure.
-
You don’t disable automatic top-ups (e.g. insurance premiums or travel card reloads), leading to overdraft fees.
-
Your DBS or POSB account is linked to a credit facility, and the overdraft is triggered unknowingly.
-
You close a CPF-linked bank account without updating your CPF, IRAS, or HDB records, causing payment failures.
To avoid this, always ensure your account is in good standing before requesting closure. Any unpaid charges or automated withdrawals could quietly snowball — and end up dragging your credit score down.
SingSaver x Citigold Exclusive Offer
Get up to S$1,800 Upsized Cash via PayNow, 75,000 Max Miles by HeyMax (worth S$1,350), an Apple iPad (A16) 11" Wi-Fi 128GB + Apple Watch Series 12 (GPS), 46mm Aluminium Case bundle or an Apple iPhone 18 Pro 512GB (worth S$2,199) when you open a Citigold account and meet the qualifying fresh funds deposit and additional requirements within 3 calendar months of account opening.
Plus, get an additional S$200 Cash when you deposit S$350,000 in the second month and maintain the funds until gift fulfilment. Valid till 1 November 2026. T&Cs apply.
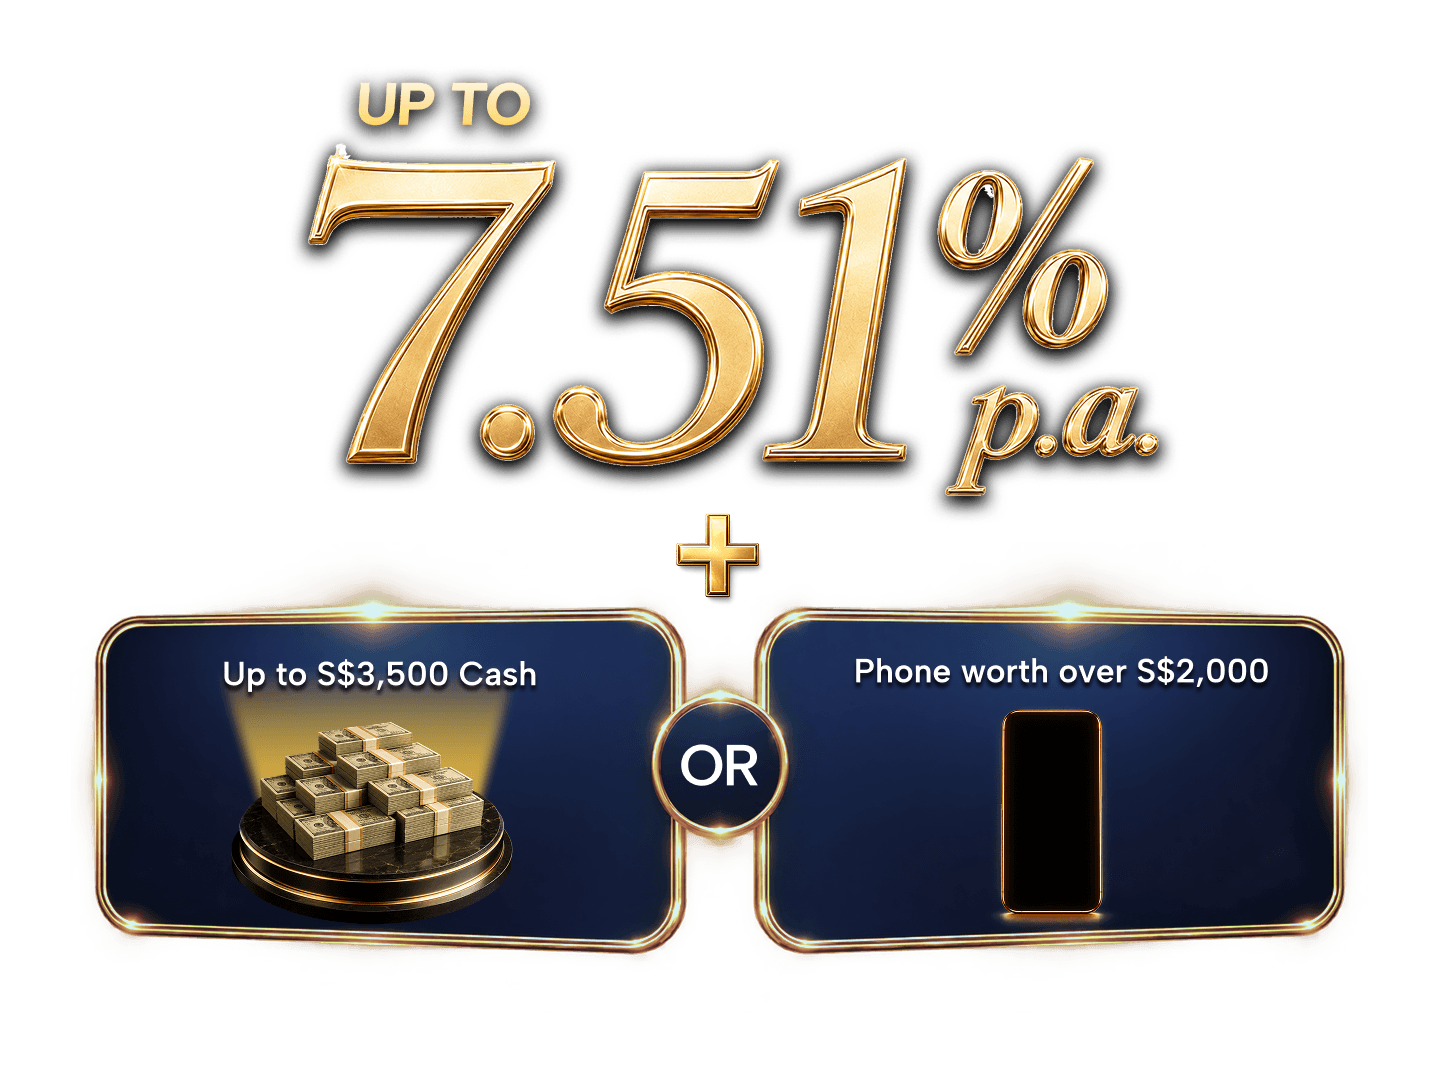
Citigold Exclusive Benefits and Privileges 💎
Enjoy up to 7.51% p.a. interest when you join Citigold and open a Wealth First account. You'll also get an additional S$500 Cash when you sign up as an Accredited Investor (AI) and S$1,000 Cash for every S$100,000 in investment or insurance purchases by the third calendar month of account opening.
Plus, enjoy preferential time deposit rates of up to 2% p.a. on 6-month SGD deposits and 1.40% p.a. on 3-month SGD deposits. Valid till 1 November 2026. T&Cs apply.
What you need to know about credit bureaus in Singapore
Learn how to access your credit report and ensure your financial records are accurate and up-to-date.
How to close your bank account the right way
Here’s a simple checklist to help you close your bank account cleanly — and avoid any credit-related headaches:
-
Cancel all GIRO arrangements
Check for linked subscriptions, telco bills, insurance premiums, or utility payments and terminate them properly. -
Transfer out all funds
Empty the account, but leave a small buffer for any pending charges or fees that haven’t cleared. -
Unlink PayNow and other services
Remove your account from PayNow, PayLah!, DBS Remit, or other linked payment services. -
Update CPF, IRAS, HDB, and LTA records
If your account is linked to CPF refunds or tax payouts, update the relevant agencies with your new bank details via SingPass. -
Monitor the account for at least one full billing cycle
Keep the account active temporarily to catch any delayed payments or charges. -
Request written confirmation of closure
Ask your bank for official proof that the account has been closed with no outstanding issues. -
Consider downgrading to a basic account
If you're unsure, switching to a no-fee option lets you maintain access without the hassle of full closure.
Done right, closing a bank account in Singapore is low-risk — but only if you check all the right boxes. Take a few extra minutes to wrap things up properly, and your credit score will remain untouched.
About the author
SingSaver Team
At SingSaver, we make personal finance accessible with easy to understand personal finance reads, tools and money hacks that simplify all of life’s financial decisions for you.