Best Ways to Invest Money in 2026
Updated: 13 Oct 2026

Written bySingSaver Team
Team
⚡ Quick Answer
| Product Name | Min. Deposit | Min. Commission Fee | Min. Trading Fee |
|---|---|---|---|
| S$3,000 | US$0 * | 0 % | |
| S$2,000 | - | S$0.99 /order | |
| S$2,000 | - | 0.03 % |
Disclaimer: The information on this page is for general educational and informational purposes only and should not be considered financial or investment advice.

The short answer
The best ways to invest money in Singapore depend on your goal: government-backed options like SSBs and T-bills for safety, index funds and ETFs for long-term growth, and dividend stocks or REITs for regular income.
There are numerous ways to invest your hard-earned money in Singapore, from high-yield savings accounts to stocks and bonds. The right mix for you comes down to three things: your financial goals, your risk tolerance, and how long you can leave your money invested.
The sheer variety of options can be overwhelming, especially if you're new to investing. This guide covers how to invest money in Singapore step by step, then compares 16 different ways to invest, from the lowest risk to the highest.
>> Compare cash management accounts and find the option that fits your investment needs.
What is the best and safest way to invest money in Singapore?
If capital protection is your priority, the best and safest way to invest money is through government-backed or bank-held instruments. These offer modest but predictable returns:
Singapore Savings Bonds (SSBs): Fully backed by the Singapore Government. You can redeem them in any month without losing your principal.
Treasury bills (T-bills): Short-term government securities with six-month or one-year tenors. You receive the full face value at maturity.
Fixed deposits: These lock in a guaranteed rate for a set period. Deposits at SDIC member banks are insured up to S$100,000 per depositor per bank.
High-yield savings accounts: These keep your money fully liquid while earning more than a regular savings account.
The trade-off is that the safest options rarely beat inflation by much over the long term. Most investors keep their emergency fund and near-term savings here, and put long-term money into growth assets.
Decision Guide
How to invest money in Singapore in 5 steps
1. Build an emergency fund first. Set aside three to six months of expenses in an accessible, low-risk account before you invest. Then a market dip won't force you to sell.
2. Clear high-interest debt. Credit card balances charge interest well above what most investments can reliably return. Paying them down is effectively a guaranteed return.
3. Define your goal and time horizon. Money you need within one to three years belongs in lower-risk options. Money for goals five or more years away can take on more market risk.
4. Choose the right account. To buy SGX stocks, you can hold shares in your own CDP account or through a broker's custodian account. For hands-off investing, a robo-advisor works. For tax-advantaged retirement investing, look at SRS or CPFIS.
5. Start small and stay consistent. A regular savings plan or monthly dollar-cost averaging spreads out your entry price. It also takes the guesswork out of timing the market.
Before You Compare
Know your risk tolerance
Lower-risk options suit capital preservation.
Confirm your time horizon
Longer horizons can absorb more short-term volatility than near-term goals.
Decide hands-on vs hands-off
Robo-advisors and index funds suit a passive approach; individual stocks require closer monitoring.
Check minimum deposit requirements
Brokerage minimums range from S$0 to S$3,000+ depending on the platform.
Best brokerage accounts for online stock trading
| Products | Min. Commission Fee (SG Stocks) | Min. Deposit | Min. Commission Fee (US Stocks) | Min. Trading Fee | ||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
S$0 | S$1000 | US$0 | 0 % | |||||||||
S$0 * | S$3000 | US$0 * | 0 % | |||||||||
S$0 | S$2000 | US$0 | 0.03 % | |||||||||
 | S$0 | S$2000 | S$0 | S$0.99 /order | ||||||||
US$1 | S$1000 | US$1 * | N/A | |||||||||
S$0 | S$1000 | N/A | 0 % | |||||||||
16 best investment options this year
There are various types of investments available in Singapore, each catering to different financial goals and risk appetites. Consider these investment options this year, ranging from low-risk to high-risk alternatives:
1. High-yield savings accounts
While not technically an investment, high-yield savings accounts provide an accessible and low-risk way to grow your money in Singapore. Compared to regular savings accounts, high-yield accounts may yield higher interest rates. As such, they're generally an appealing option for those who don't want to take a significant risk yet want to earn a return on their cash.
For those seeking potentially higher returns on uninvested cash, some brokerage firms offer accounts with rates comparable to high-yield savings accounts.
SingSaver x Citigold Exclusive Offer
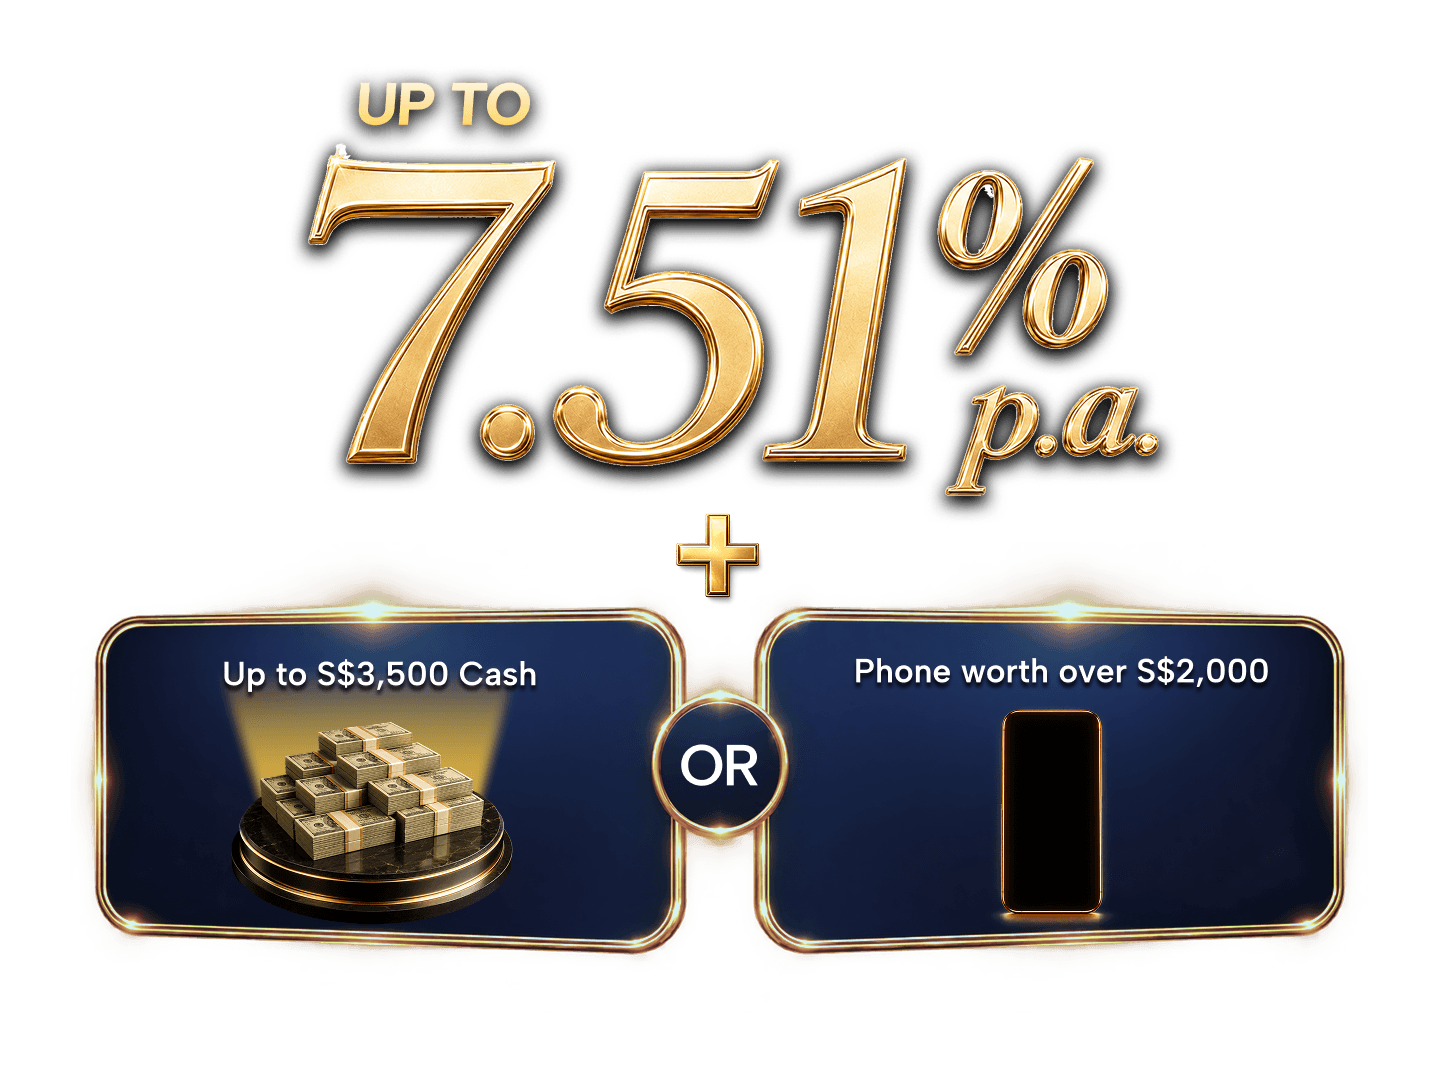
Get up to S$1,800 Upsized Cash via PayNow, 75,000 Max Miles by HeyMax (worth S$1,350), an Apple iPad (A16) 11" Wi-Fi 128GB + Apple Watch Series 12 (GPS), 46mm Aluminium Case bundle or an Apple iPhone 18 Pro 512GB (worth S$2,199) when you open a Citigold account and meet the qualifying fresh funds deposit and additional requirements within 3 calendar months of account opening.
Plus, get an additional S$200 Cash when you deposit S$350,000 in the second month and maintain the funds until gift fulfilment. Valid till 1 November 2026. T&Cs apply.
Citigold Exclusive Benefits and Privileges 💎
Enjoy up to 7.51% p.a. interest when you join Citigold and open a Wealth First account. You'll also get an additional S$500 Cash when you sign up as an Accredited Investor (AI) and S$1,000 Cash for every S$100,000 in investment or insurance purchases by the third calendar month of account opening.
Plus, enjoy preferential time deposit rates of up to 2% p.a. on 6-month SGD deposits and 1.40% p.a. on 3-month SGD deposits. Valid till 1 November 2026. T&Cs apply.
2. Fixed deposit accounts
Fixed deposit accounts, or FDs, can let you grow your savings with a guaranteed return. Similar to Certificates of Deposit (CDs) in other countries, this option involves depositing a fixed sum of money with a bank for a specified period, known as the lock-in period. In return, the bank offers a fixed interest rate that’s usually higher than regular savings accounts.
3. Government bonds
Government bonds are one of the safest ways to grow your money in Singapore, making them especially appealing if you value capital preservation over chasing high returns. When you invest in a government bond, you’re essentially lending money to the Singapore Government, which is widely regarded as one of the most creditworthy governments in the world.
In Singapore, the two most common options for individual investors are Singapore Savings Bonds (SSBs) and Treasury bills (T-bills). While both are government-backed, they serve different needs depending on how long you can commit your money.
Singapore savings bonds (SSBs)
SSBs are designed for individuals looking for a low-risk, flexible investment that works well for long-term savings.
A key feature of SSBs is their step-up interest structure. Interest rates increase the longer you hold the bond, up to a maximum tenure of 10 years. If you hold the bond to maturity, you’ll receive the full long-term return. If you need your money earlier, you can redeem your investment after the first month without any penalty or loss of principal.
Treasury bills (T-bills)
T-bills are short-term government securities with maturities of six months or one year. They are typically used by investors who want to park their money safely for a fixed period while earning a return that may be higher than a regular savings account.
Unlike SSBs, T-bills do not pay interest periodically. Instead, they are sold at a discount to their face value. When the T-bill matures, you receive the full face value, and the difference represents your return.
How to choose between SSBs and T-bills
The right choice depends on how long you can commit your funds and whether you need flexibility.
SSBs are better suited for long-term savings with the option to redeem anytime, while T-bills are more appropriate for short-term cash that you are confident you won’t need before maturity.
4. Corporate bonds
A type of fixed-income security, corporate bonds are issued by companies to raise capital for business expansion, refinancing, or operational needs. In Singapore, corporate bonds can offer higher potential returns than government bonds, but that upside comes with additional risk.
Because of these risks, many investors use corporate bonds as part of a diversified portfolio rather than relying on them as a sole investment. Bond funds and ETFs can also provide exposure to multiple issuers, helping spread risk across sectors and companies.
5. Money market funds
Money market funds are invested in short-term, low-risk debt securities like government bonds and treasury bills. They offer investors a relatively safe and liquid investment option with a stable return. Additionally, professional fund managers handle these funds by investing in a diversified portfolio of short-term yet high-quality debt instruments.
Where to buy money market funds: You can purchase these funds directly from banks or through fund platforms like Moomoo, Syfe, and CMC Markets.
>> Discover the best low-risk investments to store your emergency funds
SingSaver x moomoo Exclusive Offer
Open a Moomoo account and fund a minimum of S$2,000 to get S$130 Cash via PayNow, S$140 Grab Vouchers or 8,000 Max Miles by HeyMax. Valid till 1 November 2026. T&Cs apply.
6. Mutual funds
Mutual funds are a popular investment option in Singapore, offering investors access to a diversified portfolio of assets such as stocks, bonds, or other securities. These funds pool money from multiple investors, allowing you to spread risk more efficiently than investing in individual securities on your own.
7. Index funds
Index funds are passively managed funds that aim to replicate the performance of a specific market index, such as the Straits Times Index (STI) or the MSCI World Index. Instead of trying to beat the market, index funds are designed to match the index’s returns as closely as possible.
Like mutual funds, index funds are usually priced and traded once a day after markets close, based on their net asset value. While this means they don’t offer intraday trading like ETFs, they are still a straightforward and efficient way to gain broad market exposure without frequent buying and selling.
SingSaver x Webull Exclusive Offer
Open a Webull account and fund a minimum of SGD3,000 to receive S$110 Cash. Fund SGD10,000 to get S$250 Cash, S$50 eCapitaVoucher + Samsung Galaxy Buds4 Pro (worth S$349) (total worth S$399), or 13k Max Miles by Heymax (worth S$234). Or, top up from as low as S$35 to get a Dyson Purifier Cool™ Gen 1. Valid till 11 October 2026. T&Cs apply.
8. Exchange-traded funds (ETFs)
Exchange-traded funds (ETFs) are a versatile investment option in Singapore that combine the diversification benefits of funds with the flexibility of stock trading. Like mutual funds, ETFs pool investors’ money to invest in a diversified basket of assets such as stocks, bonds, or commodities. However, unlike mutual funds, ETFs are traded on stock exchanges, allowing investors to buy and sell them throughout the trading day at market prices.
SingSaver x Longbridge Exclusive Offer
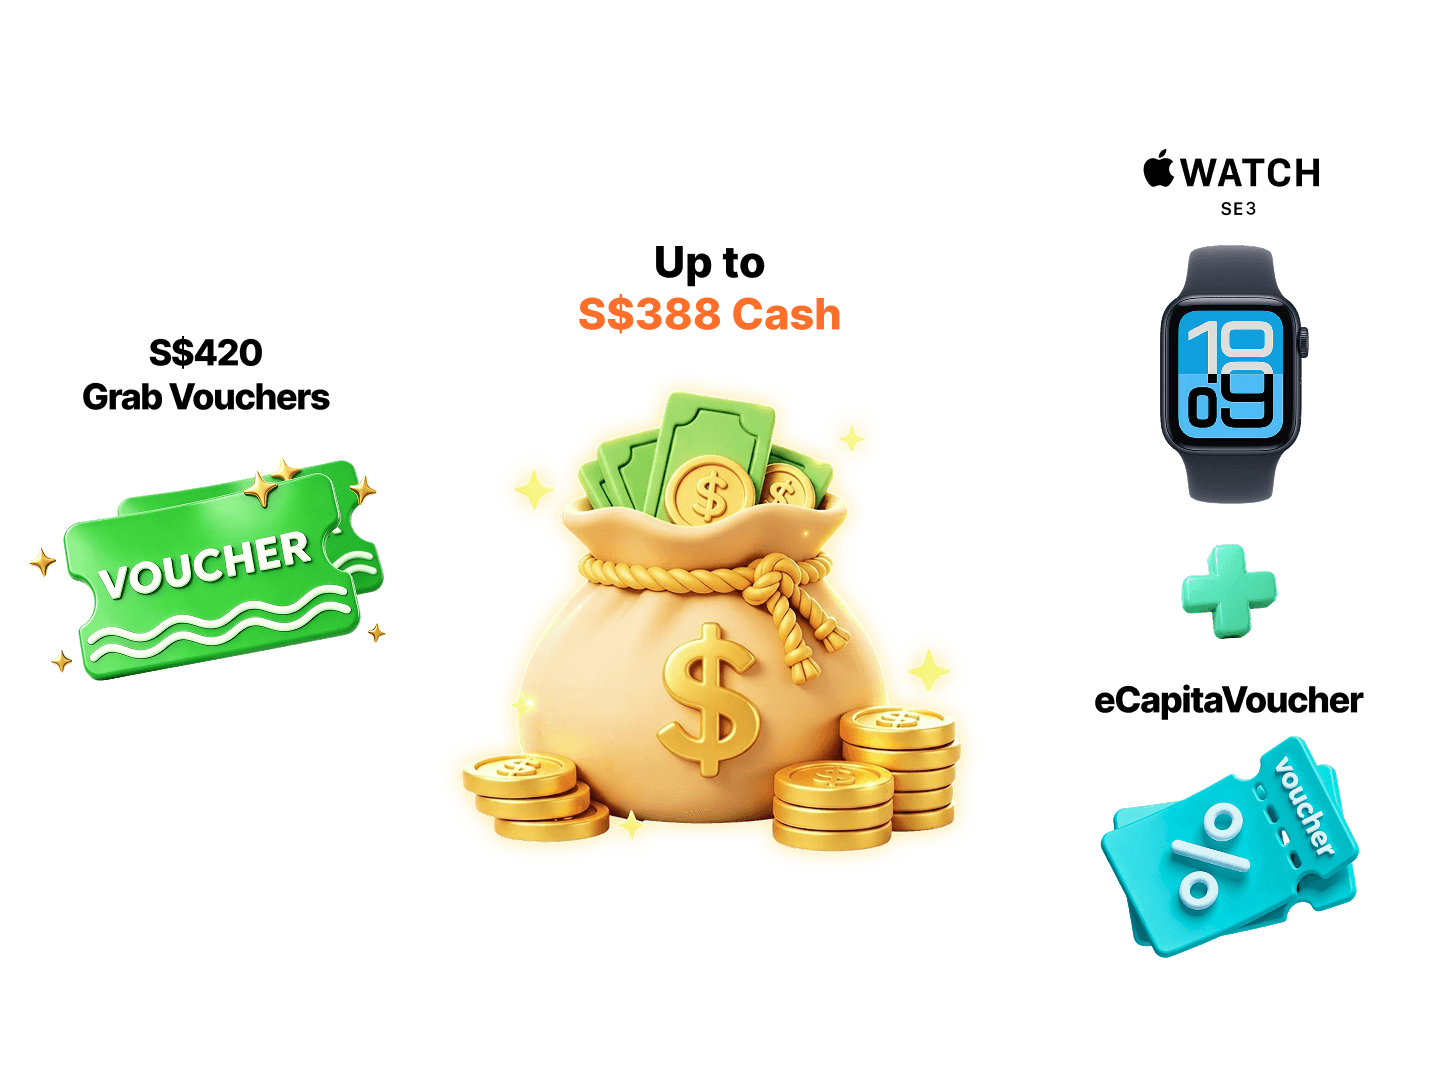
Get S$388 Cash, S$420 Grab Vouchers, or an Apple Watch SE Gen 3 40mm (GPS) (worth S$349) + S$50 eCapitaVoucher Bundle (total worth S$399) when you apply and get approved for a Longbridge SG account, fund a min. of S$2,000, make at least 1 trade and maintain the assets for 30 days from the day after meeting the deposit criteria. Valid till 18 October 2026. T&Cs apply.
9. Stocks
Stocks are one of the most well-known investment options, offering the potential for higher returns over the long term, but also coming with greater volatility. When you buy a stock, you’re purchasing a share of ownership in a company, which means your investment value rises or falls based on the company’s performance and broader market conditions.
SingSaver x CMC Markets Exclusive Offer
Open a CMC Markets account and get 2,500 Max Miles by HeyMax (worth S$45), an upsized S$20 cash via PayNow or S$40 Grab Voucher. Valid till 1 November 2026. T&Cs apply.
10. Dividend stocks
Dividend stocks are a popular choice among Singapore investors who want regular income in addition to potential long-term growth. These stocks pay out a portion of a company's profits to shareholders, usually on a quarterly or semi-annual basis.
In Singapore, dividend stocks are often associated with blue-chip companies, particularly banks, telecommunications firms, and REITs. Many of these companies have established track records of paying consistent dividends, making them appealing to income-focused investors.
If you're looking for how to invest and earn money on a regular basis, reinvesting dividends can compound your returns over time. You can also take the payouts as income once you need them.
>> Learn more about high-dividend stocks and how to invest in them
SingSaver x IG Markets Exclusive Offer
Get S$50 Cash, S$70 eCapitaVoucher, or 4,000 Max Miles by HeyMax (worth S$72) when you open an IG Markets account and make a min. deposit of S$500 and make at least 1 trade within 30 days of opening your account. Valid till 1 November 2026. T&Cs apply.
11. CPF Investment Scheme (CPFIS)
The CPF Investment Scheme (CPFIS) lets you invest a portion of your CPF savings to potentially earn higher returns than CPF's base interest rates. CPFIS is split into two accounts, each with different rules and risk profiles.
CPFIS-OA (Ordinary Account):
After setting aside the first S$20,000 in your Ordinary Account, you can invest the remaining balance in products such as unit trusts, ETFs, bonds, and shares. This option is commonly used by CPF members who want their OA savings to work harder over the long term.
CPFIS-SA (Special Account):
The Special Account is more conservative by design and is intended for retirement savings. Investments are limited to lower-risk instruments such as Singapore Government Bonds and selected unit trusts, provided you maintain at least S$40,000 in your SA.
Important note for members aged 55 and above:
From age 55 onwards, CPF rules change. Your Special Account is closed, and SA savings are transferred to your Retirement Account (RA), up to the Full Retirement Sum (FRS). As a result, CPFIS-SA investing, including strategies commonly referred to as "SA shielding", is no longer applicable for members aged 55 and above. Any remaining CPF savings beyond the RA are held in the Ordinary Account and are subject to CPFIS-OA rules instead.
What's coming next: A new voluntary Lifetime Retirement Investment Scheme, announced at Budget 2026, is slated for 2028. It will offer curated, low-cost life-cycle investment options alongside the existing CPFIS.
12. Supplementary Retirement Scheme (SRS)
The Supplementary Retirement Scheme (SRS) is a voluntary programme designed to help you save for retirement while lowering your taxable income. Contributions qualify for tax relief. Only 50% of withdrawals made from the statutory retirement age are taxable, and you can spread withdrawals over 10 years to reduce your tax further.
SRS money can be invested in a wide range of products, including stocks, bonds, SGS, SSBs, fixed deposits, unit trusts, ETFs, and insurance products. That flexibility makes SRS useful if you want to build a diversified, retirement-focused portfolio beyond CPF.
13. Cash management accounts
Cash management accounts are investment-style accounts that typically place your cash into low-risk instruments such as money market funds and short-term bonds. They’re designed to offer better yield potential than a regular savings account, while keeping your funds relatively accessible.
Common reasons investors use cash management accounts include:
-
Higher yield potential than standard savings (though not guaranteed)
-
High liquidity (typically easy deposits/withdrawals)
-
Useful for short-term parking of funds (e.g., emergency funds or “waiting to invest” cash)
Some platforms may also allow SRS funds, depending on the provider and product structure.
SingSaver x Chocolate Finance Exclusive Offer
Get up to S$120 Cash via PayNow or up to S$130 Grab Vouchers when you apply for a Chocolate Finance account via SingSaver, fund a min. of S$1,000 in your first deposit and maintain the amount for 60 days from date of account opening. Plus, enjoy up to 2% p.a. return on your first S$20k. Valid till 1 November 2026. T&Cs apply.
14. Robo-advisors
Robo-advisors are digital platforms that use algorithms to build and manage investment portfolios based on your goals, timeline, and risk tolerance. Most robo-advisors invest using diversified ETFs, and they handle rebalancing automatically. Platforms such as StashAway and Syfe also let you set up recurring deposits so you invest consistently.
Key benefits include:
- Lower fees than traditional advisory (varies by platform)
- Built-in diversification through ETF portfolios
- Convenience and automation (goal-setting, recurring deposits, auto-rebalancing)
As with any market-based investment, returns are not guaranteed, and portfolios can decline during market downturns.
15. Real estate investment trusts (REITs)
REITs let you invest in a portfolio of income-generating real estate assets without buying property directly. In Singapore, S-REITs are listed on the SGX and cover sectors like retail, office, industrial/logistics, and hospitality.
Why investors consider REITs:
-
Diversification across multiple properties (and sometimes regions)
-
Income potential through distributions (REITs typically pay out most of their taxable income)
-
Liquidity (listed and tradable like stocks)
-
Useful as an income-oriented portion of a broader portfolio
However, REIT prices and distributions can be affected by interest rates, financing costs, occupancy/rent trends, and property sector cycles.
16. Cryptocurrencies
Cryptocurrencies are digital assets secured by cryptography and commonly built on blockchain technology. They can be highly volatile, and prices may swing sharply based on market sentiment, regulation, macro conditions, and project-specific risks.
Common ways people gain exposure include:
-
Cryptocurrency exchanges (buy/sell/trade crypto assets)
-
Digital wallets (storage; some allow in-app purchases)
-
DeFi platforms (higher complexity and risk; smart contract and platform risks)
-
Crypto index funds/ETFs (where available, typically via regulated products)
-
Investing in blockchain/crypto-related companies (indirect exposure via equities)
Because risk is significantly higher than most traditional asset classes, crypto exposure is usually kept as a small slice of a diversified portfolio (if used at all).
How to shape an investment strategy that fits you
After reviewing the investment options available in Singapore, the next step is to figure out how they fit together to suit your personal situation. A good investment strategy isn’t just about returns; it’s about choosing an approach you can stay comfortable with over time.
Your preferences around involvement, risk, and time horizon all influence what a sensible portfolio looks like for you.
Hands-on or hands-off: finding your investing approach
Some investors prefer to be closely involved, researching markets, tracking news, and making frequent portfolio adjustments. This approach offers greater control but also requires time, discipline, and the ability to make decisions during volatile periods.
Others prefer a more automated experience. By using diversified funds, professionally managed portfolios, or digital platforms, these investors aim to grow their money without needing to monitor markets constantly. This approach can be more practical for those with limited time or less interest in day-to-day decision-making.
Selecting investments based on involvement level
Investors who favour a lower-maintenance approach may choose broad-based funds that follow market indices or diversified portfolios designed for long-term growth. These options tend to focus on consistency and cost efficiency rather than trying to outperform the market.
Considering full-service investment solutions
For some investors, managing investments independently isn’t the priority. Full-service options such as relationship-managed banking or advisory platforms offer portfolio construction, monitoring, and access to a wider range of investment opportunities.
These services can be useful if you value professional guidance and convenience, but they often come with higher fees. It’s worth weighing whether the additional support justifies the cost relative to your needs and portfolio size.
Understanding how much risk you’re comfortable taking
Risk tolerance isn’t just about numbers — it’s also about how you react emotionally to market swings. Knowing where you stand can help prevent panic-driven decisions during periods of volatility.
Higher-risk investing styles
Investors with a higher tolerance for risk often prioritise growth and are willing to accept larger fluctuations in portfolio value. This may involve allocating more capital to equities, emerging markets, or alternative assets.
Lower-risk investing styles
More cautious investors tend to focus on protecting capital and maintaining stability. Their portfolios may include a greater proportion of bonds, income-generating assets, or lower-volatility investments.
Building a balanced risk profile
Many investors fall somewhere in between. By combining growth-oriented and defensive assets, it’s possible to pursue long-term returns while managing downside risk. The exact balance should reflect both your financial goals and your comfort with uncertainty.
Matching investments to your time horizon
How long you plan to stay invested plays a major role in determining suitable investment choices.
Investing with a longer runway
If your goal is many years away, short-term market movements tend to matter less. A longer horizon gives investments more time to recover from downturns, which can make growth-focused assets more appropriate despite their volatility.
Investing for nearer-term goals
When your timeline is shorter, flexibility and capital preservation become more important. Investors saving for near-term expenses often prioritise stability over growth to reduce the risk of needing funds during a market dip.
Why diversification still matters
Diversification helps reduce reliance on any single investment, sector, or market. By spreading your portfolio across different asset types and regions, you lower the impact of individual setbacks.
While diversification doesn’t remove risk entirely, it can help create more consistent performance over time and reduce the likelihood of major losses tied to a single exposure.
Ultimately, the goal is to build a portfolio that supports your financial objectives — and one you’re comfortable sticking with through both calm and turbulent markets.
About the author
SingSaver Team
At SingSaver, we make personal finance accessible with easy to understand personal finance reads, tools and money hacks that simplify all of life’s financial decisions for you.
The information on this page is for educational and informational purposes only and should not be considered financial or investment advice. While we review and compare financial products to help you find the best options, we do not provide personalised recommendations or investment advisory services. Always do your own research or consult a licensed financial professional before making any financial decisions.