Why Did My Credit Score Go Down? 9 Possible Reasons
Updated: 11 Dec 2025
Written byAfina Najib
Senior Content Editor - Singapore
Disclaimer: The information on this page is for general educational and informational purposes only and should not be considered financial or investment advice.
A drop in your credit score can be a cause for concern, since it directly affects your ability to secure loans, mortgages, and other credit facilities. Understanding what can affect your credit score is the first step to fixing it — and in some cases, realising there's nothing to fix at all.
Start by checking your credit report to see exactly what changed. Below are ten common reasons your score may have dropped, with actionable tips for each.
Find the right credit card for you in no time. 💳✨
Compare exclusive offers on SingSaver across cashback, miles, and rewards cards—plus enjoy stackable welcome gifts.
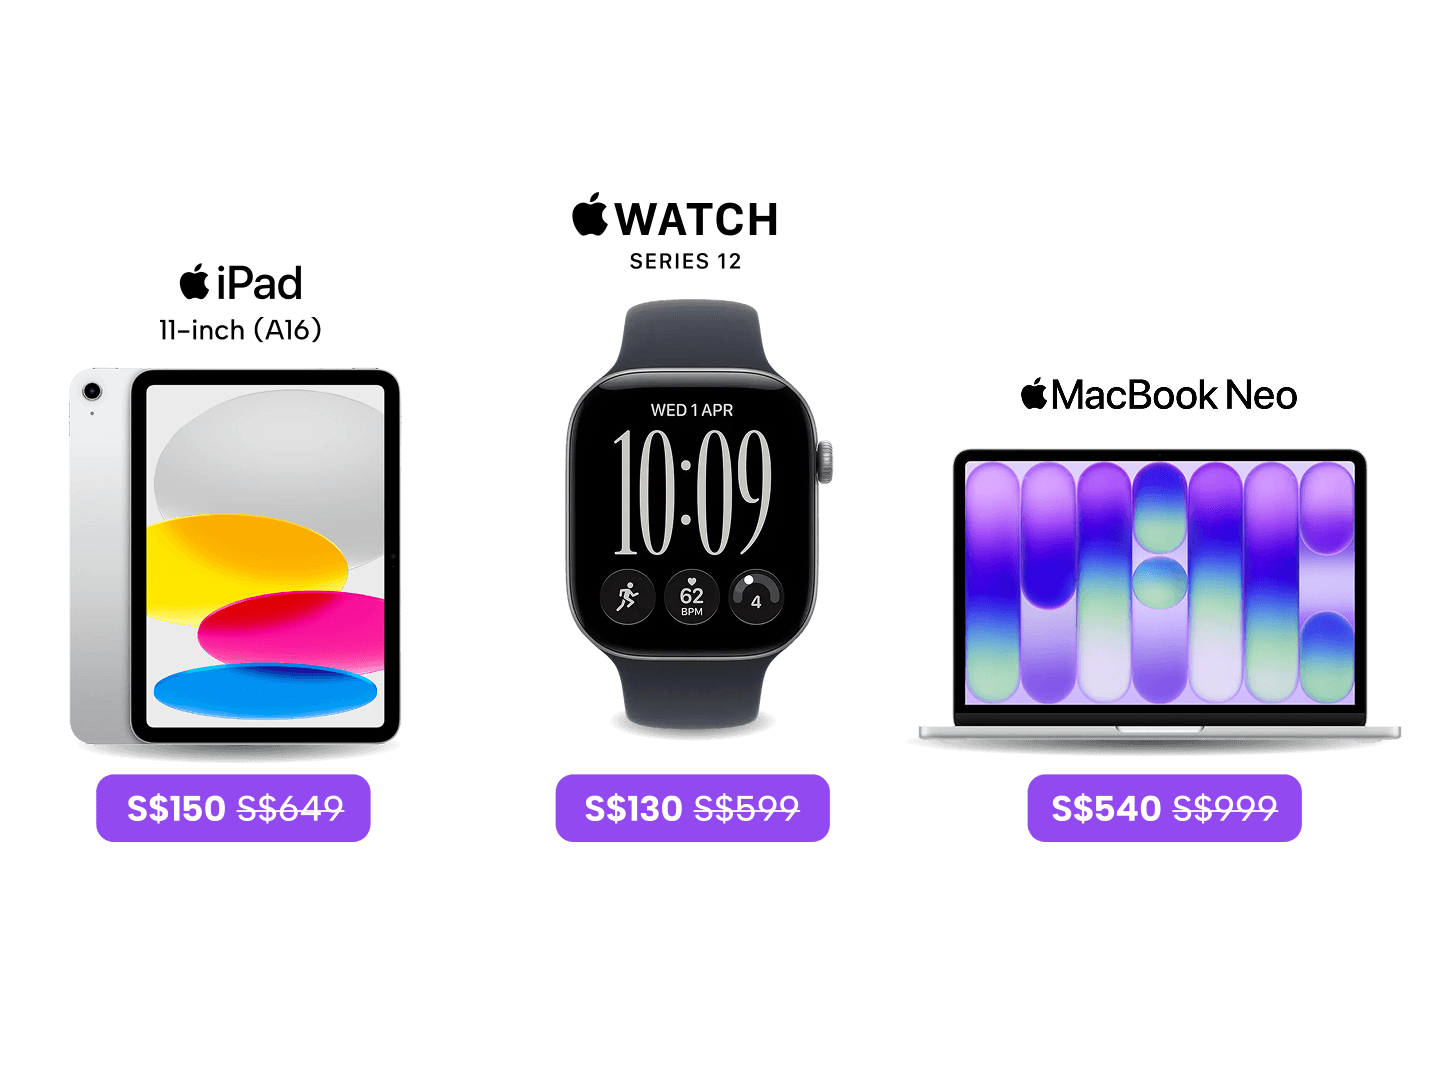
Upgrade to a premium Apple device for less! 🍎
Turn your reward into a sleek Apple tablet, headphones or laptop with a top-up starting from just S$130. Apply for select credit cards and take your pick. T&Cs apply.
Before You Compare
Pull your latest credit report first
Confirm exactly what changed before assuming the worst
Check the date of the drop
Match it against any recent applications, closures, or payoffs
Rule out errors or fraud
Look for unfamiliar accounts or inaccurate payment history
Separate a dip from a real problem
Small fluctuations are normal; only large drops need action
1. Being late with your payments
Payment history is one of the most significant factors influencing your credit score in Singapore. Lenders view it as a strong indicator of your reliability in managing debt. Even a single missed payment can hurt your score — across credit card bills, personal loan repayments, housing loan instalments, utilities, or telco bills. The impact generally worsens with each subsequent late payment or if a pattern develops.
Tips for addressing it
- Set up reminders: Use calendar alerts, phone notifications, or banking app reminders for due dates
- Automate payments: Enrol in auto-pay or GIRO to eliminate the risk of forgetting
- Prioritise essential bills: If money's tight, protect housing loans and utilities first
- Contact creditors early: If you expect to miss a payment, reach out beforehand to discuss options
Find out your credit score for free
You don’t have to spend money to check your credit score.
2. Your credit utilisation ratio is too high
Your credit utilisation ratio — the amount of credit you're using versus your total available credit — is a major factor lenders weigh. A S$10,000 limit with S$8,000 charged puts you at 80% utilisation, which signals financial strain even if you pay the minimum on time.
Tips for addressing it
- Keep utilisation below 30% to demonstrate responsible credit management
- Pay off balances quickly, ideally in full each month
- Request a credit limit increase cautiously, only if you won't be tempted to overspend
- Prioritise high-interest debt to reduce both cost and utilisation
3. Errors in your credit report
Inaccuracies — misspelled names, accounts that aren't yours, wrongly-flagged late payments, or closed accounts listed as open — can unfairly lower your score. Check your credit report from Credit Bureau Singapore (CBS) regularly.
Tips for addressing it
- Obtain your report from CBS
- Document the errors with supporting evidence
- Submit a dispute through CBS's official process
- Follow up until the dispute is resolved

SingSaver Personal Loan Cashback Offer
Enjoy one of the lowest interest rates from 0.90% p.a. (EIR from 1.75% p.a.) and up to S$6,500 in cashback when you apply for a personal loan via SingSaver. Valid till 30 September 2026. T&Cs apply.
4. Identity theft and fraud
Identity theft occurs when someone illegally obtains your personal information (NRIC, credit card details) and uses it to open accounts or run up debt in your name — directly damaging your credit score through unpaid bills, late payments, and inflated credit utilisation you never authorised.
Tips for addressing it
- Monitor your credit report regularly — CBS's My Credit Monitor (MCM) flags unfamiliar activity automatically
- Be cautious sharing personal information, especially NRIC and card details
- Strengthen online security with strong passwords and multi-factor authentication
- Report identity theft immediately to the police and CBS, who can flag your report
5. An authorised user on your credit card account is affecting your outstanding balance
An authorised user's spending adds to your total balance, which can push your credit utilisation above 30% even if your own habits haven't changed. Disagreements over repayment can also lead to late payments that you're ultimately responsible for.
Tips for addressing it
- Set clear spending limits and repayment agreements upfront
- Monitor statements for both your own and the authorised user's activity
- Consider alternatives like prepaid or strictly-limited supplementary cards
- Remove authorised users if necessary to regain full control
6. You took out a joint loan or credit card application
Co-signing makes you legally responsible for the debt if the primary borrower defaults — missed payments appear on your report, and the outstanding debt counts toward your own obligations.
Tips for addressing it
- Assess the borrower's financial stability before co-signing
- Understand your legal obligations — you're liable, not just a reference
- Explore alternatives like secured loans instead
- Limit co-signing to situations you're genuinely confident in
SingSaver x DBS/POSB Personal Loan Exclusive Offer
Enjoy interest rates from 1.48% p.a. (EIR from 3.22% p.a*) when you apply for a DBS/POSB Personal Loan. Plus, get S$900 bonus cash on top of up to 3% cashback when you apply for a loan min. S$10,000 with a min. tenure of 3 years. Use the promo code (SINGSAVER) upon application. Valid till 1 November 2026. T&Cs apply.
7. You applied for multiple credit facilities too quickly
Each application triggers a hard inquiry. A single one has minimal impact, but several in quick succession can read as financial distress or an attempt to take on excessive debt.
Tips for addressing it
- Space out applications by several months where possible
- Apply only when needed, not speculatively
- Use pre-qualification tools where available — these typically use soft inquiries only
- Research thoroughly before applying to avoid multiple applications for the best credit card
8. You cancelled one of your credit cards
Closing an old card reduces your average account age and your total available credit — pushing up your utilisation ratio if your spending stays the same.
Tips for addressing it
- Keep old accounts open responsibly, even if rarely used
- Use old cards occasionally for a small recurring purchase, paid off in full
- Prioritise newer cards for active, responsible use
- Address the underlying reason for closing rather than just closing the account
SingSaver x OCBC INFINITY Cashback Credit Card Exclusive Offer
Apply for an OCBC INFINITY Cashback Credit Card via SingSaver and choose from S$380 eCapitaVoucher, S$400 Shopee Voucher, 25,000 Max Miles by HeyMax, Dyson Airstrait, or Dyson V8 Cyclone cordless vacuum. Valid till 31 October 2026. T&Cs apply.
Or, Get the Reward Upgrade You Deserve!
You can also top up from just S$80 to upgrade to the latest Dyson and Apple products, including the latest MacBook Neo 256GB Magic Keyboard. Valid till 31 October 2026. T&Cs apply.
9. You repaid your loan
Paying off a loan is a genuine financial win, but it reduces your credit mix diversity and, for long-standing accounts, shortens your average credit history — both of which can cause a temporary dip.
Tips for addressing it
- Remember the long-term benefit outweighs the short-term dip
- Keep other accounts active and well-managed to rebuild your score
- Focus on financial freedom over score optimisation
You refinanced a loan
Refinancing — moving a mortgage or personal loan to a new lender for better rates or terms — combines several of the effects above into one event: a new hard inquiry, a closed old account (shortening your credit history if it was long-standing), and a temporary shift in your credit mix. This is a common and often overlooked answer to "why did my credit score drop after refinance," since the drop isn't caused by any misstep on your part.
Tips for addressing it
- Expect a temporary dip and don't panic — it typically recovers over several months
- Avoid stacking other credit applications around the same time as a refinance
- Keep new account payments on time from day one to start rebuilding history quickly
- Weigh the interest savings against the short-term score impact — refinancing usually remains worth it for the long-term cost reduction
[Table Builder]
| What can affect your credit score | Typical Impact | How Long It Lasts |
|---|---|---|
| Late or missed payments | High | Can remain on record for years; impact fades gradually |
| High credit utilisation (>30%) | High | Resolves once a lower balance is reported |
| Credit report errors | Variable | Until disputed and corrected with CBS |
| Identity theft / fraud | High | Until flagged and resolved with CBS and the police |
| Authorised user's spending | Moderate | As long as the balance stays elevated |
| Co-signing a joint loan | Moderate–High | For the life of the co-signed debt |
| Multiple credit applications | Low–Moderate | A few months per inquiry |
| Closing a credit card | Low–Moderate | Eases as remaining accounts age |
| Paying off a loan | Low, temporary | Typically a few months |
| Refinancing a loan | Low–Moderate, temporary | Typically a few months as the new account ages |
What does having a lower score mean?
Your credit score reflects your creditworthiness — a lender's assessment of how likely you are to repay borrowed money. A lower score can mean:
- Difficulty obtaining credit: New credit cards, personal loans, car loans, or a mortgage become harder to get approved for
- Higher interest rates: Approved credit often comes with less favourable terms
- Lower credit limits: Restricting your purchasing power
- Impact beyond lending: Occasionally affecting rental applications or certain job checks
Maintaining an excellent credit score opens the door to better rates and terms. To raise your credit score after identifying the cause of a drop, focus on consistent on-time payments and utilisation under 30% — progress is gradual, but these remain the most reliable levers.
Decision Guide
Frequently asked questions about credit score in Singapore
Even if you pay on time, using more of your credit card balance than usual can lower your score until a lower balance is reported the following month. Closed accounts or reduced credit limits can also cause a drop without any change to your payment habits. If the drop seems truly unexplained, review your credit report for errors or signs of identity theft.
Refinancing a loan — whether a mortgage or a personal loan — can lower your score for a few overlapping reasons. Applying with a new lender triggers a hard inquiry, which has a small, temporary impact. Closing your old loan account shortens your average credit history if it was long-standing, and it also reduces the diversity of your credit mix if the new facility structure differs from the old one. None of this reflects poorly on your creditworthiness — it's a mechanical side effect of how the scoring model weighs account age and inquiries, and scores typically recover over the following months as the new account ages and payment history builds.
Paying off a loan is a positive financial move, but it can shorten your average credit history and reduce your credit mix diversity, especially for older accounts — causing a temporary dip.
CBS provides the main credit score in Singapore (1000–2000), but individual lenders use their own internal models that weigh income, CPF, and transaction history differently. Reporting delays can also mean lenders are working from slightly older data.
Your Bureau Score is recalculated from current credit information and will naturally shift over time. Slight changes are nothing to worry about — larger, sudden drops are worth investigating further.
About the author
Afina Najib
Spending most of her young writer's phase working as a freelancer, Afina's written for various industries ranging from e-commerce, travel to health and finance. Her expertise lies in her ability to make complex subjects like finance easy to consume for everyday readers.
The information on this page is for educational and informational purposes only and should not be considered financial or investment advice. While we review and compare financial products to help you find the best options, we do not provide personalised recommendations or investment advisory services. Always do your own research or consult a licensed financial professional before making any financial decisions.