DBS Chromo Card Review (2026): Is It Worth It in Your 20s?
Updated: 3 Nov 2026
Written byAfina Najib
Senior Content Editor - Singapore
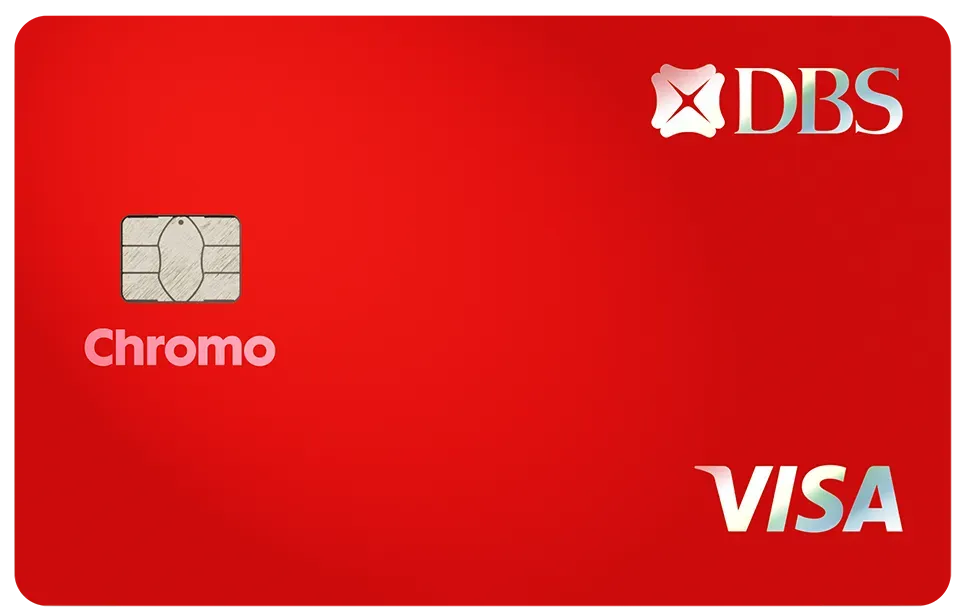
DBS Chromo Card
Disclaimer: The information on this page is for general educational and informational purposes only and should not be considered financial or investment advice.
If you’re 21 to 29 and looking for your first “real” credit card, the DBS Chromo Card is aimed squarely at you. It’s only open to applicants in that age band. DBS automatically detects your two highest-spending local categories each month and pays up to 5% cashback on them. You can also switch to 1.3 miles per dollar.
Our verdict: the DBS Chromo Card is worth it as a local cashback card if you spend at least S$500 a month across a couple of everyday categories. It’s weak as a miles card, and it earns nothing on foreign currency spend. Below, we run the actual numbers, explain the caps that limit real-world earnings, and cover who should pick something else.
DBS Chromo Card at a glance
| Feature | DBS Chromo Card |
|---|---|
| Cashback rate | Up to 5% (1% base + 4% bonus on top 2 categories) |
| Bonus categories | Dining, Travel, Shopping, Transport, Entertainment, Wellness |
| Minimum spend for bonus | S$500 per calendar month |
| Bonus cap | S$30 per category per month (reached at S$750 spend) |
| Total monthly cashback cap | S$150 (base + bonus) |
| Miles rate | 1.3 miles per S$1, uncapped (DBS Points, no expiry) |
| Overseas/foreign currency spend | 0% FX fee, but earns no rewards |
| Annual fee | S$196.20 (waived for first 5 years) |
| Miles conversion fee | S$27.25 per conversion |
| Late payment fee | S$100 |
| Finance charge | 27.8% p.a. (compounded daily) |
| Minimum income | S$30,000 (SG/PR), S$45,000 (foreigners) |
| Age to apply | 21–29 |
| Supplementary card | Not offered |
Decision Guide
How the DBS Chromo Card rewards work
You don’t choose a bonus category with Chromo. Each calendar month, DBS looks at your spending across six categories: Dining, Travel, Shopping, Transport, Entertainment and Wellness. Your two highest-spending categories automatically earn up to 5% cashback, made up of 1% base plus a 4% bonus.
Three rules shape what you actually earn:
- It runs on the calendar month, not your statement cycle. Spending on 31 March and 1 April counts towards different months, which matters if you’re timing a big purchase to clear the S$500 minimum.
- The bonus is capped at S$30 per category. That cap is reached at S$750 of spend in a category. Anything above S$750 in that category earns only the 1% base. Across two categories, the most bonus you can earn is S$60 a month.
- Total cashback is capped at S$150 a month. In practice, you’d need about S$9,000 of monthly spend to hit this cap, so the S$30 per-category bonus cap is the one that will actually limit most people.
If you don’t reach S$500 of eligible spend in a month, everything earns the flat 1% base. Category definitions are broad. For example, telco bills fall under Entertainment. Check DBS’s T&Cs for the full merchant category code list and exclusions.
How much cashback will you actually earn?
Example 1: A typical month (S$900 spend)
| Category | Spend | Base (1%) | Bonus (4%) | Cashback |
|---|---|---|---|---|
| Dining (top 1) | S$400 | S$4.00 | S$16.00 | S$20.00 |
| Shopping (top 2) | S$250 | S$2.50 | S$10.00 | S$12.50 |
| Transport | S$120 | S$1.20 | – | S$1.20 |
| Other local spend | S$130 | S$1.30 | – | S$1.30 |
| Total | S$900 | S$35.00 (3.9% effective) |
Example 2: A heavy month where the caps kick in (S$2,100 spend)
| Category | Spend | Base (1%) | Bonus (4%) | Cashback |
|---|---|---|---|---|
| Travel, local SGD bookings (top 1) | S$1,200 | S$12.00 | S$30.00 (capped; uncapped would be S$48) | S$42.00 |
| Dining (top 2) | S$600 | S$6.00 | S$24.00 | S$30.00 |
| Shopping | S$300 | S$3.00 | – | S$3.00 |
| Total | S$2,100 | S$75.00 (3.6% effective) |
Example 3: A light month (S$450 spend)
You’re below the S$500 minimum, so you earn 1% on everything: S$4.50.
The takeaway: Chromo works best when you spend S$500 to S$1,500 a month concentrated in two categories. Beyond about S$750 in any single category, your effective rate drops quickly.
Cashback or miles: which mode should you use?
You can switch your reward preference in the DBS digibank app once a month. The preference that is active on the 10th of a month applies to the previous month’s spend. This means you can see how much you spent before deciding which mode to use.
| Scenario | Cashback mode | Miles mode | Miles must be worth more than… |
|---|---|---|---|
| S$900 month (Example 1) | S$35.00 | 1,170 miles | ~3.0¢ per mile to beat cashback |
| S$450 month (missed min. spend) | S$4.50 | 585 miles | ~0.8¢ per mile to beat cashback |
| After age 30 (1.7% flat) | S$15.30 on S$900 | 1,170 miles | ~1.3¢ per mile to beat cashback |
In months where you hit S$500, cashback mode wins comfortably, because few people can redeem miles at 3¢ or more each. In months where you fall short of S$500, switching to miles before the 10th is usually the better choice. Keep in mind that each conversion to KrisFlyer, Asia Miles, Qantas or AirAsia costs S$27.25, so let points build up and convert in larger batches.
What it costs
The headline annual fee is S$196.20, but it’s waived for your first 5 years as a cardholder. Given the age-based eligibility, that covers most of the time people will hold this card. Beyond that, DBS’s standard credit card charges apply: a S$100 late payment fee if the minimum payment isn’t received by the due date, and finance charges of 27.8% p.a., compounded daily, on any revolving balance. Singapore doesn’t cap credit card interest rates or late fees by law. Instead, MAS requires banks to disclose these charges clearly on your statement. Paying your bill in full each month is the only way to avoid finance charges entirely, on this card or any other.
Who can actually get one
This is where Chromo differs most from a typical cashback card: eligibility is age-gated to 21–29 at the point of application, alongside a minimum annual income of S$30,000 for Singaporeans and PRs, or S$45,000 for foreigners. That income floor isn't a DBS-specific quirk — Singapore's Banking (Credit Card and Charge Card) Regulations require banks to verify a minimum income before extending unsecured credit, and to keep your total unsecured borrowing across all banks within a multiple of your monthly income, enforced through the Credit Bureau Singapore. If you're a student or early-career professional who doesn't yet meet S$30,000, you won't qualify for Chromo (or most standard cashback cards) — a no-income-requirement digital bank card is the realistic interim option.
Before You Compare
Check your age range
Chromo only accepts applicants aged 21 to 29 at application.
Confirm your annual income
S$30,000 for SG/PR, S$45,000 for foreigners, verified via MyInfo.
Decide: Cashback or miles
You can toggle monthly, but pick a default that matches most spend.
Estimate top 2 categories
Bonus caps at S$30/category, so map your typical monthly spend first.
Check rules after you turn 30
Rewards step down from the 4th month after your 30th birthday month.
What happens when you turn 30
You can’t apply for Chromo once you’re 30, but if you already hold the card, you keep it. You’ll keep earning up to 5% cashback (or 1.3 mpd) for 3 months after your 30th birthday month. From the 4th month, the card becomes a flat 1.7% cashback card with no minimum spend and no cap, or 1.3 mpd uncapped.
That’s a good fallback. Few Visa cards in Singapore pay 1.7% uncapped cashback on all local spend. If your spending sits well below the old caps, it’s worth keeping. If you were regularly earning close to S$60 in monthly bonus, compare it against a category card at that point.
Pros & Cons
Pros
Automatic top-2 category detection, so there’s nothing to register or remember
A low S$500 minimum spend for 5% on broad everyday categories
The annual fee is waived for 5 years
You choose cashback or miles after the month ends
1.7% uncapped cashback after 30 is a strong fallback
Cons
The S$30 per-category bonus cap limits big spenders to S$60 of bonus a month
1.3 mpd is uncompetitive as a miles card
Foreign currency spend earns nothing, despite the 0% FX fee
You can’t apply once you’re 30
No supplementary cards
Alternatives to consider
| Card | Best for | Bonus rate | Min. spend | Monthly cap | Overseas spend |
|---|---|---|---|---|---|
| DBS Chromo Card | Mixed everyday local spend, ages 21–29 | 5% on top 2 of 6 categories | S$500 | S$30/category, S$150 total | 0% FX, no rewards |
| Maybank XL Cashback Card | Overseas spenders; 5% across all bonus categories | 5% | S$500 | S$80 [confirm] | Earns cashback [confirm] |
| UOB Absolute Cashback Card | Simple flat cashback, no age limit | 1.7% flat (2% promo to 31 Jan 2027) [confirm] | None | Uncapped | [confirm] |
Is the DBS Chromo Card worth it?
Yes, for the right person. If you’re a Singaporean or PR aged 21 to 29, earn at least S$30,000, and spend S$500 to S$1,500 a month across everyday categories, Chromo will typically return 3.5 to 4% with no annual fee for five years and no category management. Use it in cashback mode, and switch to miles only in months where you miss the S$500 minimum.
It’s the wrong card if you want to collect miles, if a lot of your spending is in foreign currency, or if one category regularly takes more than S$750 of your monthly spend. In those cases, a dedicated miles card, an overseas spending card, or a higher-cap cashback card will earn more.
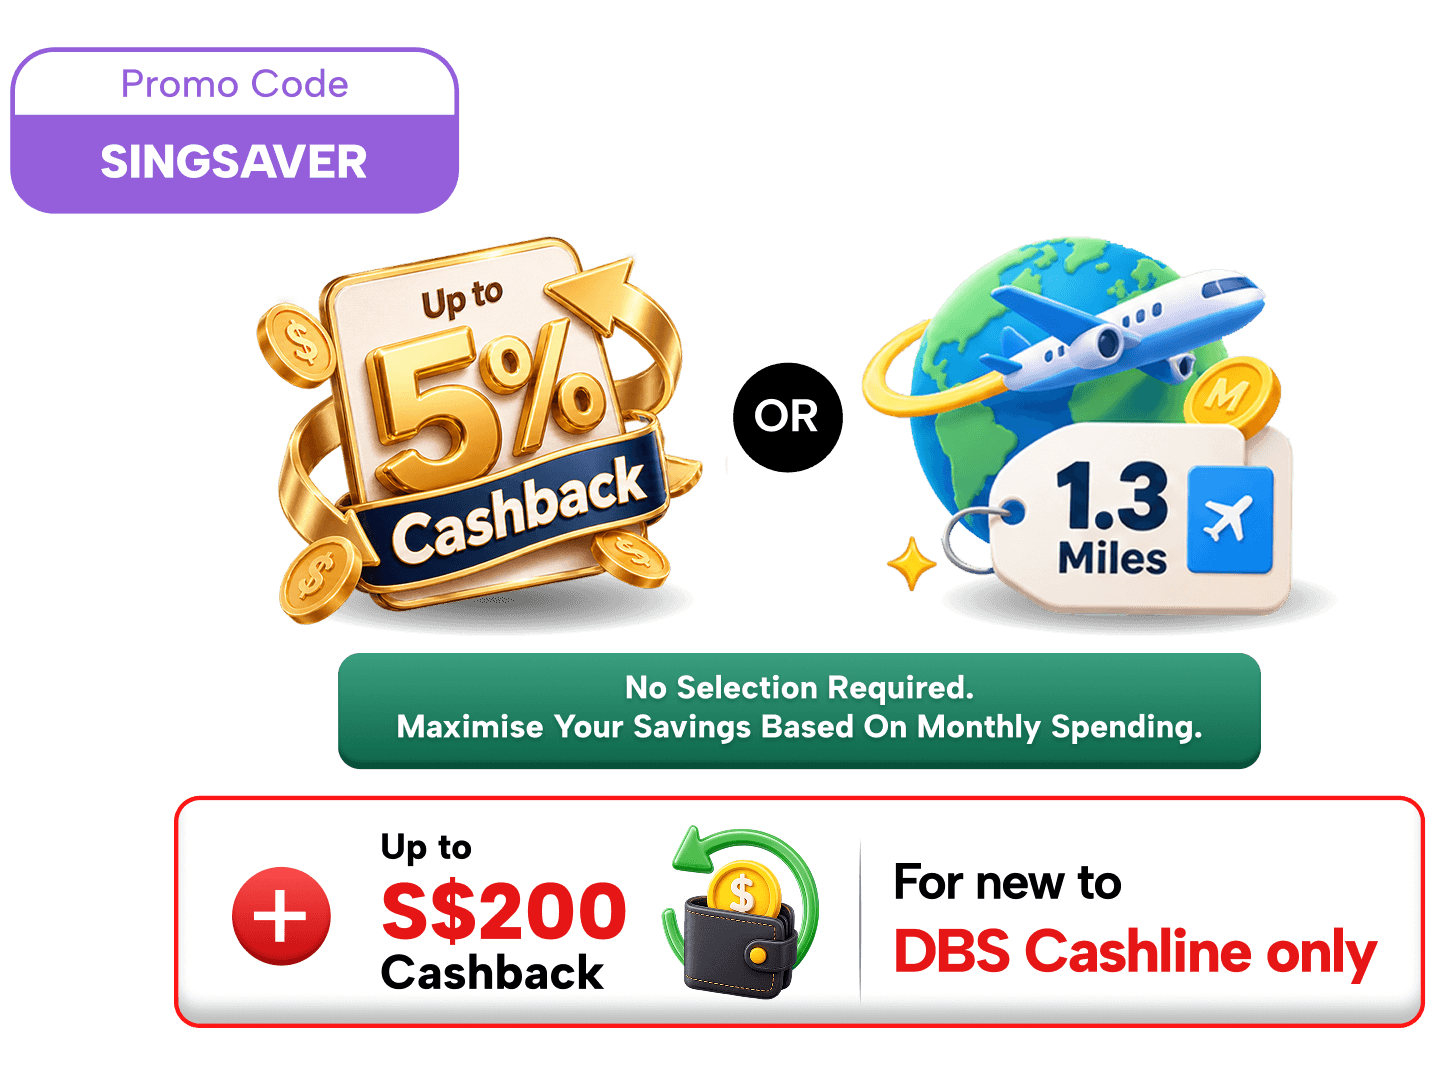
SingSaver x DBS Chromo Card Exclusive Offer
Enjoy S$320 Cash, S$350 Shopee Voucher, 22,000 HeyMax Miles, Beats 360 headphones, or Dyson Cool™ AM07 Tower Fan when you apply and spend a minimum of S$500 within 30 days of card approval. Use promo code SINGSAVER. Valid till 15 October 2026. T&Cs apply.
Plus, get up to S$200 cashback on Cashline when you select “Cashline” in your application on the DBS/POSB website, and fulfil other requirements. Valid till 15 October 2026. T&Cs apply.
FAQ
Can I apply for the DBS Chromo Card if I’m 30 or older?
No. Applications are limited to ages 21 to 29. Existing cardholders keep the card after turning 30, and their rewards change to 1.7% flat cashback from the 4th month after their 30th birthday month.
Does the DBS Chromo Card earn rewards overseas?
No. It charges 0% FX fees, but foreign currency and overseas transactions earn no cashback or miles.
How much spend do I need to max out the bonus?
S$750 in each of your top two categories, which earns S$30 bonus each. Beyond that, extra spend in those categories earns only the 1% base.
Is cashback or miles better on the DBS Chromo Card?
Cashback, in any month where you spend at least S$500. Miles only come out ahead in months where you fall short of the minimum spend.
Does the minimum spend follow my statement cycle?
No. Chromo tracks spend by calendar month.
Can I get a supplementary card?
No. DBS doesn’t issue supplementary cards for Chromo.
About the author
Afina Najib
Spending most of her young writer's phase working as a freelancer, Afina's written for various industries ranging from e-commerce, travel to health and finance. Her expertise lies in her ability to make complex subjects like finance easy to consume for everyday readers.
The information on this page is for educational and informational purposes only and should not be considered financial or investment advice. While we review and compare financial products to help you find the best options, we do not provide personalised recommendations or investment advisory services. Always do your own research or consult a licensed financial professional before making any financial decisions.