Is Now a Good Time to Refinance My Mortgage?
Updated: 7 Oct 2026
Written byAfina Najib
Senior Content Editor - Singapore
Disclaimer: The information on this page is for general educational and informational purposes only and should not be considered financial or investment advice.
Unlock the lowest home loan interest rates
Discover the best home loan rates to ensure you secure the most affordable financing and achieve your homeownership goals.
Is now a good time to refinance your mortgage?
For many homeowners, yes. Home loan rates fell sharply through 2025 and reached lows in mid-2026, and fixed and floating packages are now priced close together. If your lock-in has ended, your loan has likely moved to a much higher board rate, and switching could cut your monthly instalment significantly.
But falling interest rates aren't the only reason to refinance. This guide covers when to refinance your mortgage, how often to do it, the steps involved, and what to weigh up before you switch.
Should you refinance your mortgage now?
Before You Compare
Check when your lock-in ends
Refinancing before then usually means a penalty and clawed-back subsidies.
Give notice on time
Most banks need about 3 months' written notice to redeem your loan.
Add up legal and valuation fees
Check if the new bank subsidises them, and if you'd have to repay subsidies.
Ask your bank to reprice first
Repricing is faster and cheaper, but may not offer the lowest rate.
Current mortgage refinance rates in Singapore
| Package type | Indicative rate (September 2026) | Notes |
|---|---|---|
| 2-year fixed | From about 1.39%–1.45% p.a. | Lowest rates usually need larger loan sizes |
| Floating (SORA-linked) | 3M Compounded SORA (~1.19%–1.23%) + spread from 0.20% | SORA has edged up since mid-2026 |
| HDB concessionary loan | 2.60% p.a. | You can refinance from HDB to a bank, but not back |
| Typical board rate after lock-in | Often 3.50%–4.50% p.a. | What many borrowers pay if they don't refinance |
Indicative rates only. Actual rates depend on your property type, loan size and profile, and change often. Compare current packages before you decide.
When to refinance your mortgage: what to consider first
Before you refinance your home loan, weigh up these factors:
- Cost of refinancing: Refinancing involves legal fees, valuation fees and possibly fire insurance, unless the new lender subsidises them. If you exit during your lock-in period, you'll usually also pay an early redemption penalty, often around 1.5% of the amount redeemed. You may also have to return any legal or valuation subsidies your current bank gave you. Make sure your savings will outweigh these costs.
- Long-term housing plan: Most home loan packages in Singapore have a lock-in period of two to three years. If you plan to sell soon, refinancing may not be worthwhile, as you may not reach the break-even point before you sell.
- Your current loan timeline: The ideal time to start planning is around four months before your lock-in ends, because most banks require three months' written notice to redeem your loan.
>> MORE: Best car refinance loans and rates
How often should you refinance your mortgage?
Many Singapore homeowners review their mortgage every two to three years, when each lock-in period ends. That's when promotional rates typically expire and your loan moves to a higher rate. You don't need to refinance every time, but it's worth comparing packages at each lock-in expiry.
Refinancing more often than that usually means paying lock-in penalties and clawbacks. That rarely pays off unless rates have dropped significantly.
How to refinance your mortgage loan: steps to refinance
Here are the steps to refinance your mortgage in Singapore:
- Check your current loan terms. Find your lock-in end date, notice period, early redemption penalty and any subsidy clawback clauses.
- Ask your bank for a repricing offer. Switching to a new package with your current bank is faster and usually cheaper. Use it as a benchmark.
- Compare packages from other banks. Look at the rate for each year, the spread after the promotional period, the lock-in, and any fee subsidies.
- Work out your break-even point. Add up legal, valuation and other costs, then divide by your monthly savings to see how long it takes to recover them.
- Apply and accept the Letter of Offer. The new bank will assess your income, credit record and debt servicing ratios (TDSR, or MSR for HDB flats and ECs), and value your property.
- Give notice to your current bank. Most banks need about three months' written notice to redeem your loan.
- Let the lawyers complete the switch. The new bank's appointed law firm handles the redemption. Your new loan takes over on the completion date.
Refinancing typically takes about six to eight weeks to complete, compared with two to three weeks for repricing.
The benefits of refinancing your home loan
The main reason Singaporeans refinance is to secure a lower mortgage rate, which can lead to substantial savings over the life of your loan. It can also help if your financial goals or circumstances have changed and you want to reduce your monthly repayments.
Mortgage refinance tips
Always compare rates from several lenders, not just your current bank. Whether you're a first-time homeowner or refinancing, compare the best home loans for the most competitive rates.
The savings can be significant. Take a S$700,000 loan with 25 years remaining:
- At a 4.00% board rate, your monthly instalment is about S$3,700.
- At a 1.45% refinancing rate, it's about S$2,780.
That's a difference of roughly S$900 a month. Use a refinancing calculator to estimate your own savings.
Bank promotional rates usually apply only for the first year or two, after which the package moves to a higher rate. Always check what the rate and spread will be after the promotional period, and compare offers across several banks.
Refinancing for your financial goals
Now that you have a better understanding of when you can refinance your home loan, it's time to understand more about the potential benefits of refinancing your mortgage. In Singapore, this financial flexibility can be particularly helpful in managing your cash flow more effectively or strategically aligning your repayments with significant life events, such as planning for retirement income, funding children's higher education, or pursuing long-term investment planning.
Want to reduce your monthly repayments to free up cash? You can extend your loan tenure (up to the age cap of 65 or 75, depending on the specific bank's policies). Prefer to pay off your loan faster and save substantially on overall interest costs? You can shorten the tenure, reducing your total interest paid — especially if your income has increased significantly in recent years or if you’ve successfully cleared other outstanding debts.
That’s why it’s essential to select the loan term that carefully aligns with your current life stage, evolving financial goals, and long-term aspirations, such as planning for a comfortable retirement or strategically investing elsewhere, because this critical decision significantly impacts your long-term financial well-being and security.
In Singapore, you can also refinance without necessarily changing your original loan term by precisely matching the new loan to your desired payoff date — such as aiming to pay off the mortgage before retirement. For instance, if you’ve already paid five years on an initial 30-year loan, you can refinance into a 25-year term to maintain your original schedule.
It's highly advisable to ask your bank to show you different loan amortisation (meaning the schedule of payments and how much of each payment goes toward the principal and interest) scenarios to thoroughly compare monthly costs and the total amount of interest payable over the loan's life.
Loan type: Fixed or floating?
When you refinance, you can also switch from a floating-rate loan to a fixed-rate loan, or the other way round, depending on market conditions and your risk tolerance.
Floating-rate packages are pegged to SORA or board rates. They can be cheaper when rates are stable or falling, but your instalments will change with the benchmark. Fixed-rate packages give you predictable monthly payments for the lock-in period, which helps with budgeting and financial planning.
In 2026, fixed and floating rates are unusually close. That means you can lock in certainty for little or no extra cost, while floating packages benefit if SORA falls again.
Banks also offer hybrid packages that combine fixed and floating elements. Read the fine print carefully, beyond the headline advertised rate. Check how and when the rate adjusts, all fees, and any repricing clauses.
>> MORE: How will rising housing loan interest rates in Singapore impact you?
⚡SingSaver x Trust Personal Loan Flash Deal⚡
Enjoy low interest rates from 1.00% p.a. (EIR 2.28% p.a.) plus up to S$11,750 in cashback and rewards when you sign up for Trust Bank Personal Loan via SingSaver. Plus, receive a S$10 FairPrice E-Vouchers from Trust when you sign up with the referral code SINGSAVE. Valid till 1 November 2026. T&Cs apply.
Cashing out home equity
In Singapore, you can strategically cash-out refinance your built-up home equity when refinancing your mortgage, subject to meeting the bank's specific eligibility criteria and their individual risk assessment.
This financial tool is commonly used to fund major and often significant expenses, such as extensive home renovations to increase property value, financing children’s expensive overseas education, or pursuing potentially lucrative business opportunities.
Cash-out amounts depend heavily on the loan-to-value (LTV) limit allowed by the bank, your outstanding mortgage balance at the time of refinancing, and the bank’s overall risk appetite and lending policies. For owner-occupied properties, LTV caps in Singapore usually go up to a maximum of 75% of the property's appraised value.
However, it's crucial to note carefully that tapping into your home equity significantly increases your total loan amount and, consequently, your monthly repayments, which can strain your finances, so you must make absolutely sure you’re using the borrowed funds for a financially sound and responsible reason with a clear plan for repayment. If not, you should carefully explore other means of securing the necessary funds, such as personal loans or lines of credit, to avoid jeopardising your home ownership.
Saver-savvy tip
You don't always have to switch banks. Repricing means moving to a new package with your current bank. It's usually faster and cheaper than refinancing, as you won't need new legal work or a valuation, though some banks charge an admin fee.
Repricing also lets you change your loan terms, such as switching from a floating to a fixed rate. Ask your bank for a repricing offer first, then compare it with packages from other lenders before deciding.
Repricing vs refinancing
| Repricing | Refinancing | |
|---|---|---|
| Lender | Your current bank | A new bank |
| Legal and valuation fees | Usually none (admin fee may apply) | Yes, often subsidised by the new bank |
| Time to complete | About 2–3 weeks | About 6–8 weeks |
| Rate choice | Limited to your bank's packages | The whole market |
| Best for | Convenience and lower switching costs | Securing the lowest available rate |
Refinancing due to life changes
Banks and lenders may also perform thorough checks of your credit scores and any existing debt obligations to determine if the updated loan structure is financially viable and sustainable for the borrower. Life circumstances and situations change frequently and unexpectedly, and sometimes, your existing mortgage structure must also adapt to reflect these changes. You might therefore, want to refinance your mortgage if you encounter situations where you need to:
-
Add a spouse to the mortgage after marriage to formally share ownership and financial responsibility for the property.
-
Remove an ex-spouse or a family member from the mortgage following a divorce or a formal ownership restructuring agreement.
-
Change the primary income contributor due to evolving CPF usage regulations or shifting HDB eligibility rules.
Refinancing provides a valuable opportunity to re-evaluate the borrower profile and their current financial standing. The new bank will meticulously assess the income, CPF contributions, credit score, and mortgage servicing ratio (MSR) or total debt servicing ratio (TDSR) of the applicant(s) before granting final approval for the refinance.
SingSaver x HSBC Personal Loan Exclusive Offer
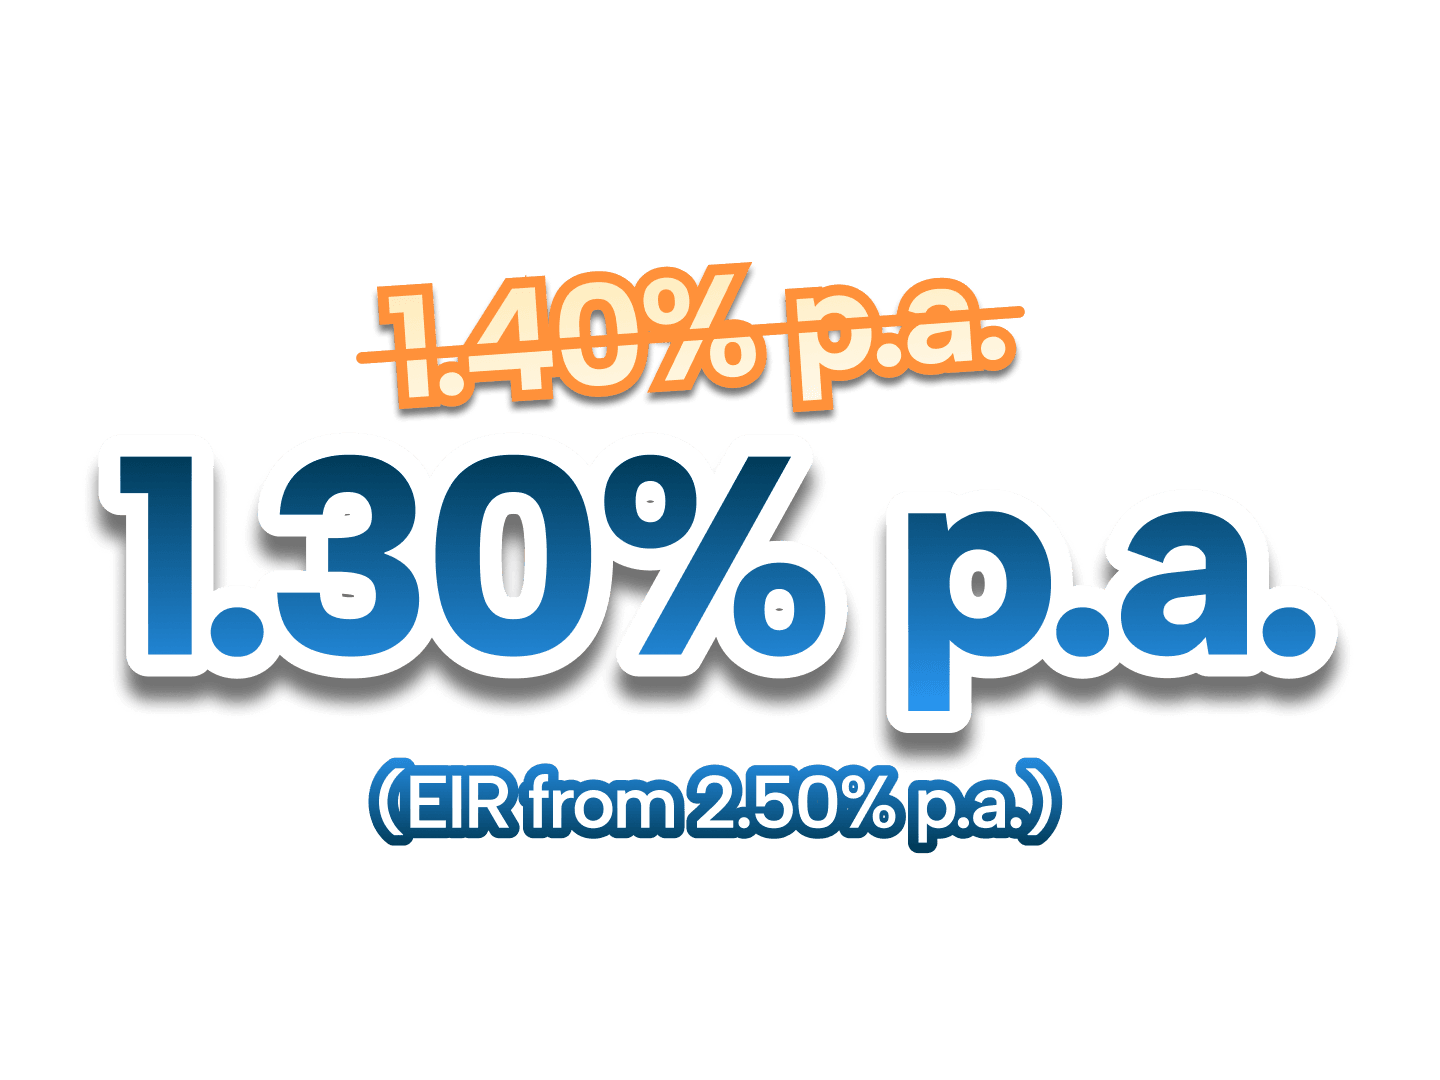
Enjoy attractive interest rates from 1.30% p.a. (EIR from 2.50% p.a.) when you apply for HSBC Personal Loan via SingSaver. Available to new and existing customers! Valid till 1 November 2026. T&Cs apply.
Frequently asked questions about refinancing your mortgage
When should I refinance my mortgage?
Start planning about four months before your lock-in period ends, since most banks require three months' notice. Refinancing is especially worth considering once your loan has moved to a board rate, or when market rates are well below your current rate.
How often can I refinance my mortgage?
There's no limit, but most homeowners review their loan every two to three years when each lock-in period ends. Refinancing during a lock-in usually triggers a penalty, so it rarely makes sense unless rates have fallen sharply.
How much does it cost to refinance a home loan?
Expect legal and valuation fees, which many banks subsidise. You may also need fire insurance. Leaving during a lock-in period usually costs an early redemption penalty, often around 1.5% of the amount redeemed, plus any clawback of earlier subsidies.
Can I refinance my HDB loan to a bank loan?
Yes. Bank rates are currently below the HDB concessionary rate of 2.60% p.a. However, once you switch to a bank loan, you can't go back to an HDB loan.
Is it better to reprice or refinance?
Repricing with your current bank is faster and usually cheaper. Refinancing with a new bank gives you access to the whole market's rates. Get a repricing offer first, then compare it with other banks' packages.
About the author
Afina Najib
Spending most of her young writer's phase working as a freelancer, Afina's written for various industries ranging from e-commerce, travel to health and finance. Her expertise lies in her ability to make complex subjects like finance easy to consume for everyday readers.
The information on this page is for educational and informational purposes only and should not be considered financial or investment advice. While we review and compare financial products to help you find the best options, we do not provide personalised recommendations or investment advisory services. Always do your own research or consult a licensed financial professional before making any financial decisions.