Online Banking: Definition, Pros & Cons, and What It Means For You
Updated: 24 Jul 2025

Written bySingSaver Team
Team
Disclaimer: The information on this page is for general educational and informational purposes only and should not be considered financial or investment advice.
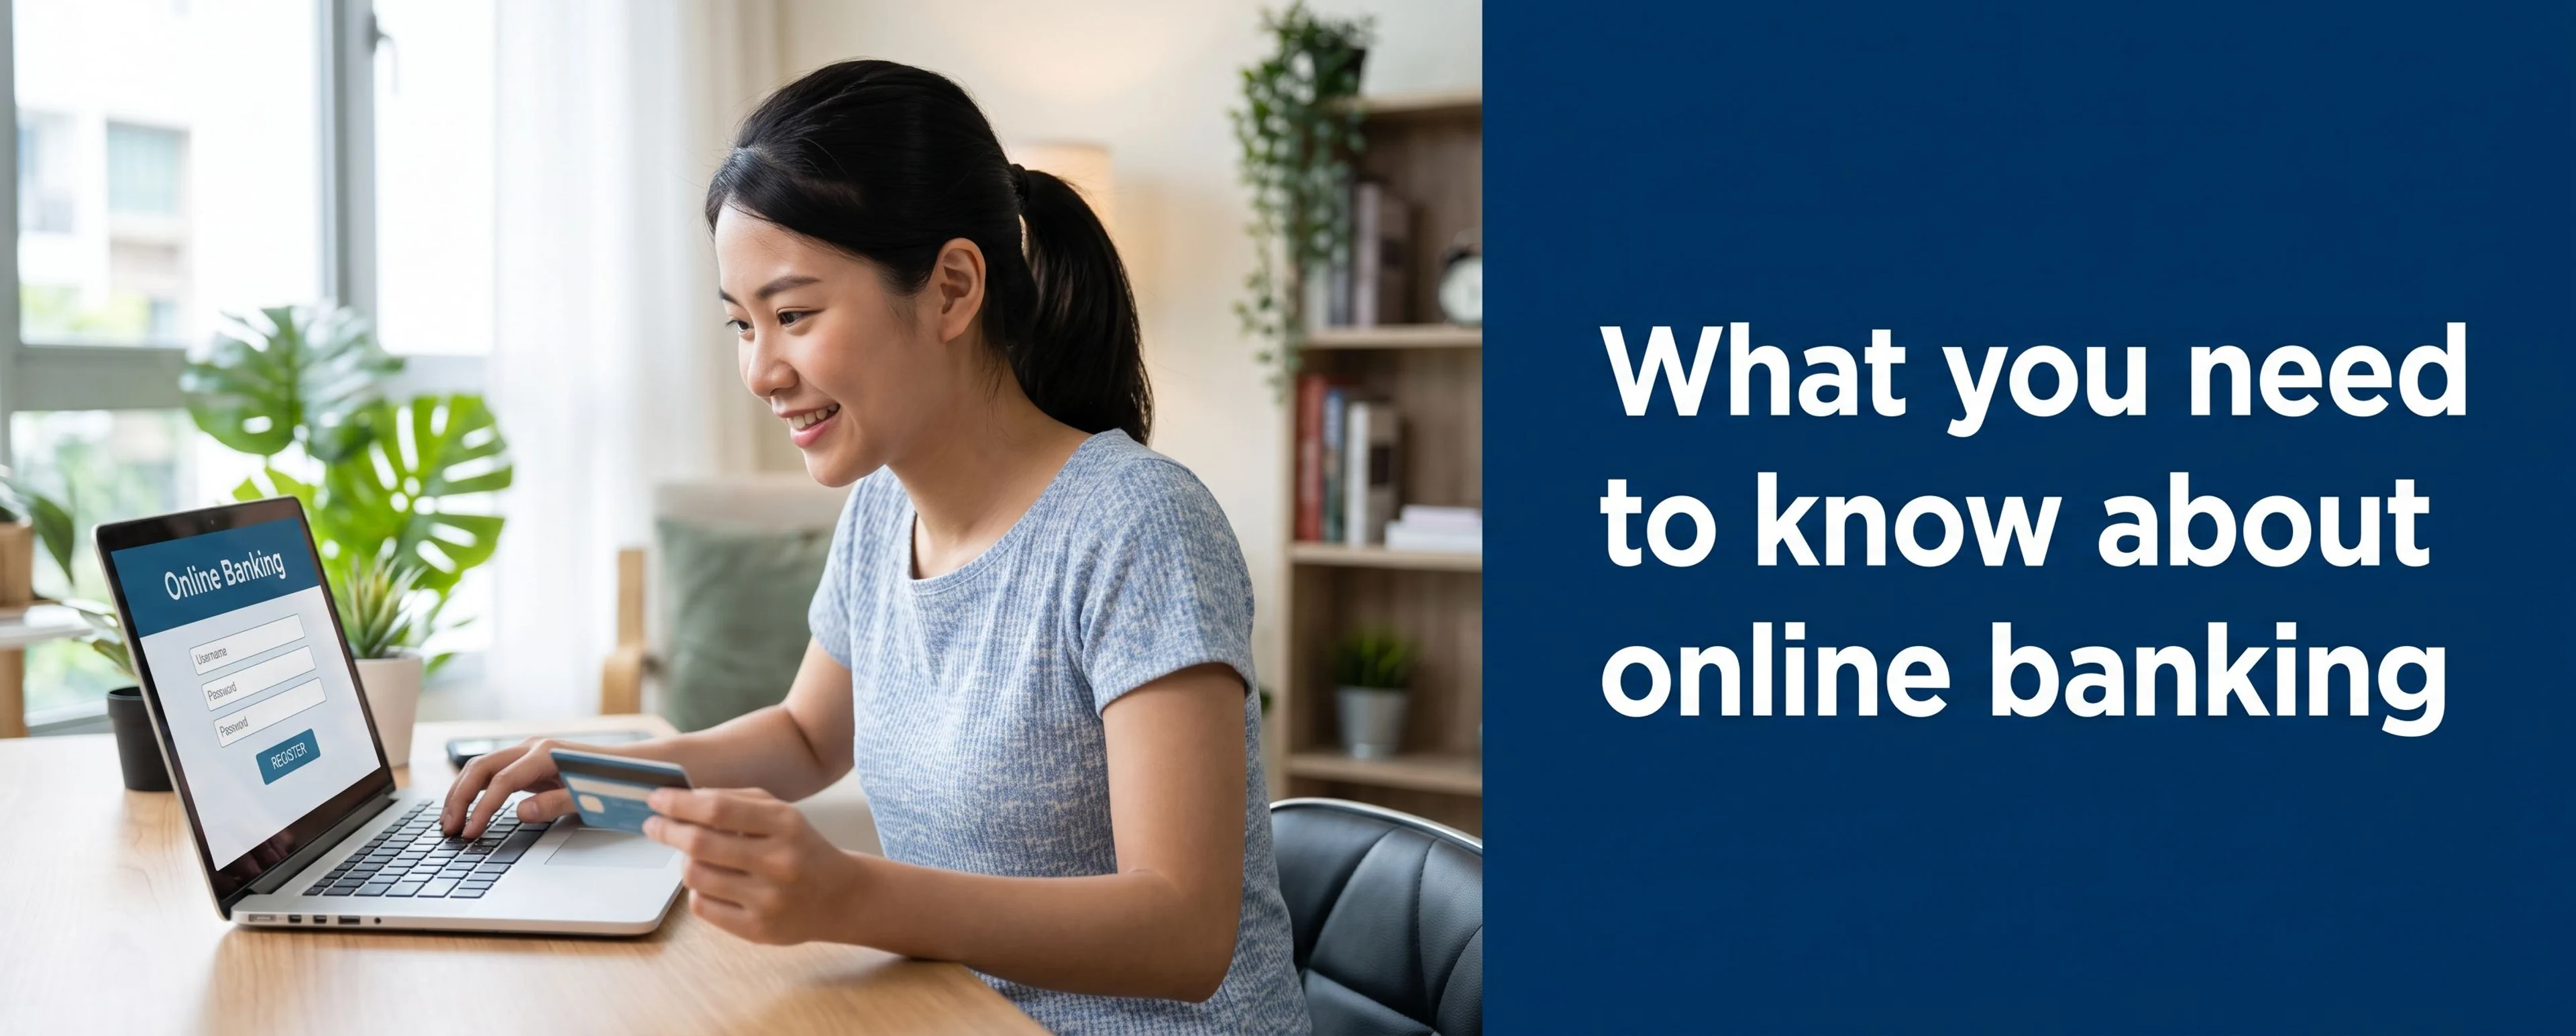
Online banking refers to accessing banking services over the internet through a website or app, without visiting a physical branch. It covers everything from checking your balance to transferring funds via FAST or PayNow, paying bills through GIRO or eBill, and applying for credit cards, loans, and insurance.
In Singapore, internet banking and online banking are used interchangeably — both describe accessing your bank account digitally, whether from a desktop browser or an app.
Online banking vs mobile banking
The terms overlap, but there's a practical difference:
| Online banking | Mobile banking | |
|---|---|---|
| Access point | Desktop or laptop browser (and apps) | Smartphone app specifically |
| Typical use | Full-service — statements, applications, complex transfers | Quick, everyday tasks — balance checks, PayNow, QR payments |
| Features | Broadest feature set, closest to branch-equivalent service | Streamlined, mobile-first UX; some features (e.g. cheque deposits via photo) are mobile-only |
In practice, most Singapore banks now build mobile-first: apps like DBS digibank and OCBC Digital carry nearly the full online banking feature set, so the distinction matters less than it used to.
Features of online banking
Online banking platforms in Singapore typically offer:
- FAST transfers, PayNow, PayLah!, and PayAnyone transactions
- Opening fixed deposits digitally
- Access to integrated investment platforms like OCBC Digital Investing
- Applying for credit cards, personal loans, and travel insurance
- Updating personal details (e.g. home address) directly in the app
- Biometric login and two-factor authentication (2FA) for security
How safe is online banking?
Singapore banks are regulated by MAS and required to use encryption, 2FA, and transaction alerts to protect your account. Online banking is generally considered safe when you follow basic precautions — but scams targeting bank customers (phishing links, fake SMS, impersonation calls) remain the biggest real-world risk, not weaknesses in the banking systems themselves.
» For a full breakdown of safe practices, see How to Keep Online Banking Safe.
Digital bank vs traditional bank
Which fits you?
Pros of online banks
With convenience and cost savings at the forefront, online banking is increasingly popular among Singaporeans.
Lower fees
Digital banks like Trust Bank and GXS, and even traditional banks' online platforms, often waive fees such as minimum balance charges. Without branch overheads, online banks can pass on savings to customers.
» Compare overdraft fees at our local banks
Better interest rates
Online-only banks and digital savings accounts frequently offer better rates than traditional banks. Trust Bank and GXS provide competitive savings rates, while traditional banks like Standard Chartered's Bonus$aver reward customers who bank digitally (salary crediting, bill payments).
» You can also supercharge your savings with a fixed deposit
Cons of online banks
While online banking is convenient, it is not without drawbacks — especially for customers who prefer in-person service or have more complex banking needs.
No physical branches
For complex needs like mortgage advisory or investment planning, the absence of a branch can be a downside. Document notarisation and large cash transactions still require an in-person visit.
Cash is harder to deposit
Cash deposits in Singapore still mainly happen at ATMs or branch counters. Digital-only banks like Trust Bank and GXS don't offer cash deposit facilities — customers typically deposit into a traditional bank first, then transfer electronically.
» Explore everything deposit-related with our overview
Fewer one-stop-hub options
Traditional banks like DBS and OCBC offer investments, insurance, and wealth management alongside banking. Digital banks tend to focus on core banking, with a narrower bundled range.
» And if you decide to do so, learn how to switch banks
Before You Compare
Check cash deposit needs
Digital banks (Trust, GXS, SeaBank) don't accept cash deposits directly
Compare minimum balance rules
Traditional banks may charge fall-below fees; most digital banks don't
Look at bundled services
Traditional banks offer wealth, insurance and loans under one login
Check interest rate conditions
Digital banks' rates may need no conditions; traditional banks may require salary crediting or spend
Best savings accounts 2026
Find a low-fee, high-interest, hassle-free savings account that suits your needs here
Online banks' standard services
Online banking platforms in Singapore are highly developed, offering services such as:
-
FAST transfers, PayNow, PayLah!, and PayAnyone transactions
-
Opening fixed deposits digitally
-
Access to integrated investment platforms like OCBC Digital Investing
-
Applications for credit cards, personal loans, and travel insurance
-
Updating personal details like home address directly through banking apps
Thanks to this extensive range, most banking needs in Singapore can be met online with minimal hassle.
Find your ideal loan in Singapore 2026
Need quick cash? Find and apply for online personal loans with fast approval, competitive rates, and flexible repayment options.
Frequently asked questions about online banking
Online banking means using the internet to access your bank account and perform transactions without visiting a branch. To get started, download your bank's app, register via MyInfo (linked to SingPass), set up 2FA, and explore the available services.
Retail internet banking (personal finance), corporate internet banking (business accounts), mobile banking (smartphone apps), and neobanking (fully digital banks with no branches).
Yes — many Singapore banks let you open an account fully online using MyInfo, which auto-fills your details and verifies your identity instantly.
Neobanks operate entirely online with no physical branches. In Singapore: Trust Bank (NTUC and Standard Chartered), GXS Bank (Grab and Singtel), and SeaBank (Sea Group). They offer simple products, attractive rates, and lower fees, but no cash deposits and a narrower product range than traditional banks.
» Learn how to open a bank account online
If you're comfortable banking digitally and want lower fees and better rates, it's a good fit. If you need personalised advice, large cash deposits, or notarised documents, you may want to keep a traditional account alongside it.
About the author
SingSaver Team
At SingSaver, we make personal finance accessible with easy to understand personal finance reads, tools and money hacks that simplify all of life’s financial decisions for you.
The information on this page is for educational and informational purposes only and should not be considered financial or investment advice. While we review and compare financial products to help you find the best options, we do not provide personalised recommendations or investment advisory services. Always do your own research or consult a licensed financial professional before making any financial decisions.