Best Credit Cards For Overseas Spending in Singapore
Updated: 1 Oct 2026
Optimise your holiday spending with attractive cashback and high air miles earn rates. Here are the best credit cards for overseas spends in Singapore.
Written byAfina Najib
Senior Content Editor - Singapore
⚡ Quick Answer
| Card | Card benefit | Annual Fee | Min. Annual Income |
|---|---|---|---|
| 1.2 - 2.4 miles / dollar | S$196.20 | S$65,000 | |
| 1.4 - 8 miles / dollar | S$261.60 | S$30,000 | |
| Unlimited 1 - 3 % cashback | No Annual Fee | S$120,000 |
Disclaimer: The information on this page is for general educational and informational purposes only and should not be considered financial or investment advice.
The best credit card for overseas spending depends on how you like to be rewarded. For miles, the HSBC TravelOne Credit Card and UOB PRVI Miles Card earn up to 2.4 miles per dollar on foreign currency spend. For cashback, the CIMB Visa Infinite Card offers unlimited cashback on travel and overseas spend. To avoid foreign transaction fees entirely, the Trust Freedom Card charges 0%.
Best credit cards for overseas spending
Overseas spending and foreign currency transactions often earn higher cashback and air miles than local spend. To get more bang for your buck, pay with a card built for overseas spending, and make sure the rewards outweigh the foreign currency fees you'll pay.
Here's how the best credit cards for overseas travel and transactions in Singapore compare. We've also covered how to activate your credit card for overseas use before you fly.
Which overseas spending card suits you?
Before You Compare
Check the FCY fee on every card
Most cards charge about 3.25%. Make sure your rewards outweigh the fee.
Look for minimum spend and caps
Bonus rates often need a monthly minimum spend and stop after a cap.
Always pay in the local currency
Decline DCC. Paying in SGD overseas usually costs you more.
Activate overseas use before you fly
Turn on overseas payments and ATM withdrawals in your bank app.
Best credit cards for overseas spending: comparison
Product | Card benefit | Foreign transaction fee | Annual fee |
|---|---|---|---|
1.2 - 2.4 miles / dollar | 3.25 % | S$196.20 | |
Unlimited 1 - 3 % cashback | 3 % | No Annual Fee | |
 | 0.4 - 2.8 miles / dollar | 3.25 % | S$196.20 |
1.4 - 8 miles / dollar | 3.25 % | S$261.60 | |
1.3 - 2.2 miles / dollar | 3.25 % | S$196.20 | |
1.5 - 2.5 % cashback | 3.25 % | S$196.20 |


Best cashback credit cards for overseas spending
Citi Cash Back Card
If great food is the reason you travel, the Citi Cash Back Card is worth a look. It earns 6% cashback on dining and groceries and 8% on petrol and private commute. All other spend earns 0.2%.
The dining and groceries rates are based on the type of merchant, so they apply overseas too. That makes the card a good companion for foodies hunting down favourite eats abroad. Even after the 3.25% foreign transaction fee, you still come out ahead.
Note that the 8% private commute rate only covers listed ride-hailing and taxi operators such as Grab and Gojek. Overseas rides on apps like Uber earn just 0.2%.
You'll need to spend at least S$800 in a statement month to unlock these rates, and cashback is capped at S$80 a month. Cashback is credited in blocks of S$10, with a minimum of S$50 each time.
📱Score a Super Smartphone Upgrade
Be the first eligible applicant at 3PM and 9PM to apply for Citi Credit Cards to score a reward upgrade to the latest smartphone worth over S$1,800! Valid till 11 October 2026. T&Cs apply.
SingSaver Citi Credit Card + Banking Bundle Offer
Score upsized S$500 Cash via PayNow in place of exisiting rewards when you apply for a Citi Credit Card, make a minimum spend of S$500 and hold a valid Citi banking account (existing or newly opened) by the end of the month following card approval. Valid till 31 October 2026. T&Cs apply.
SingSaver Exclusive Offer
Get up to S$430 Cash via PayNow, up to S$450 Shopee Voucher, 25,000 Max Miles by HeyMax, Dyson Airstrait™ straightener, or Dyson V8 Cyclone Vacuum Cleaner upon activating and spending a minimum of S$500 within 30 days of card approval. Valid till 11 October 2026. T&Cs apply.
Or, Get the Reward Upgrade You Deserve!
You can also top up from just S$100 to upgrade to the latest Dyson and Apple products, including the latest MacBook Neo 256GB Magic Keyboard. Valid till 11 October 2026. T&Cs apply.
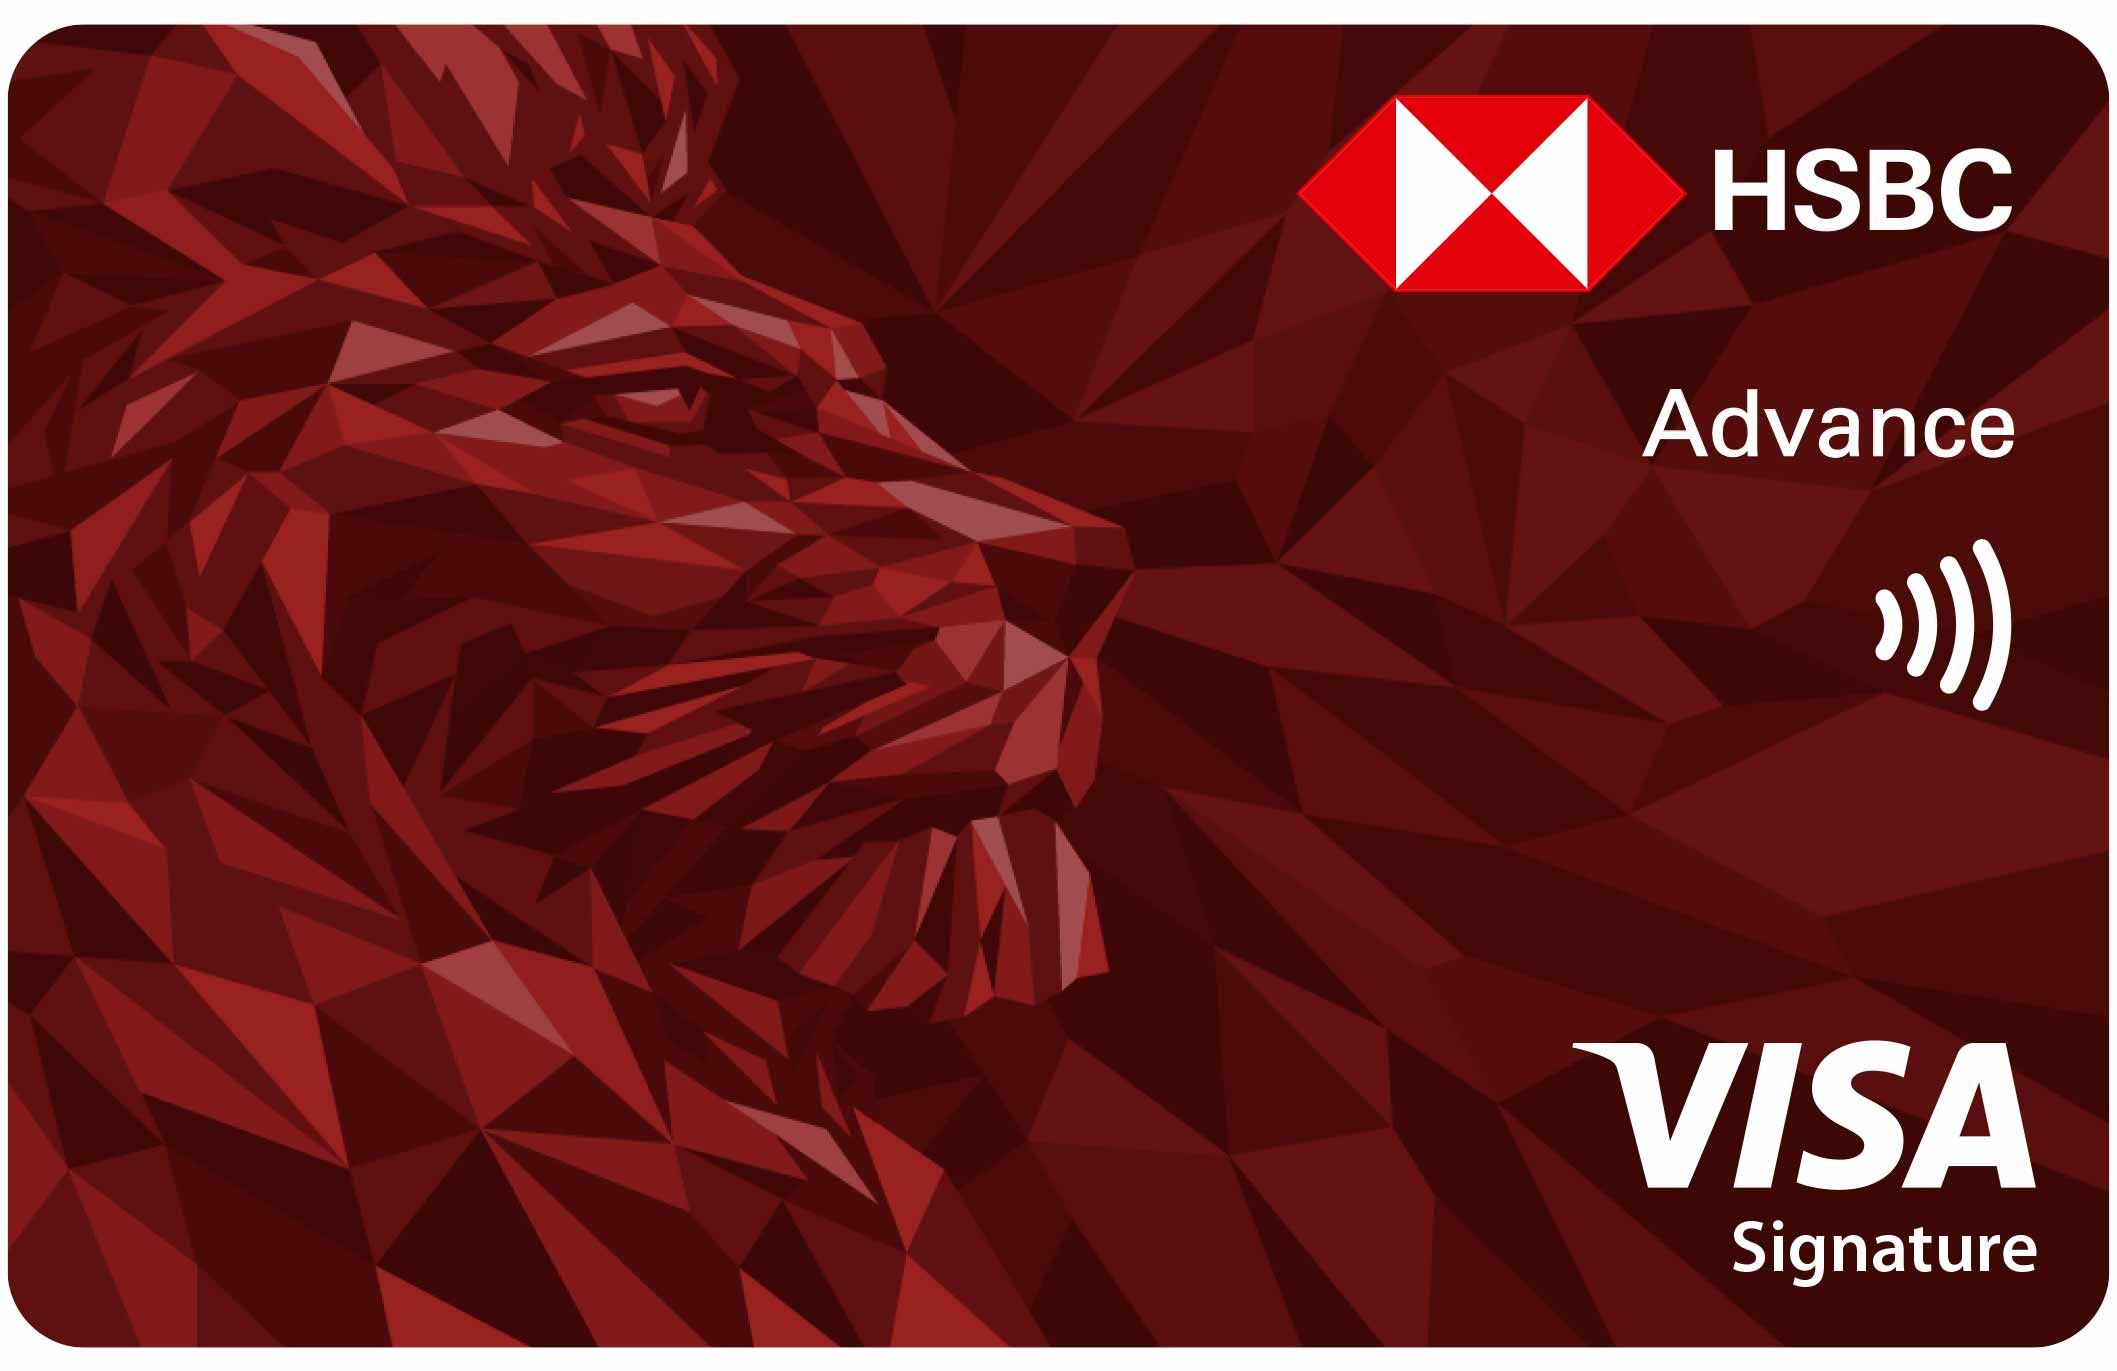
HSBC Advance Card
The HSBC Advance Card is a fuss-free cashback card with no categories to track. You earn 1.5% cashback with no minimum spend, or 2.5% if your eligible spend is above S$2,000 in a calendar month. Cashback is capped at S$70 a month, which you'll reach at S$2,800 of spend.
Where it shines for travellers is its complimentary travel insurance. Charge your full travel fare to the card and you're covered, including up to S$500,000 for accidental death or permanent disablement and up to S$1,000,000 for emergency medical evacuation.
However, its cashback rate doesn't cover the 3.25% foreign transaction fee. It's best used for travel bookings paid in SGD, rather than for foreign currency spend while you're abroad.
Note that the minimum annual income is S$65,000. It's lower for HSBC customers with at least S$50,000 in Total Relationship Balance.
CIMB Visa Infinite Card
This premium card offers unlimited cashback of 2% on travel, overseas and online foreign currency spend, and 1% on all other retail spend. That makes it an easy choice for travellers who prefer uncomplicated reward mechanics. The only requirement is a minimum spend of S$2,000 in a statement month.
It also comes with three complimentary airport lounge visits a year at more than 1,000 airports. Charge your full travel fares to the card and you and your family get complimentary travel insurance of up to S$1 million. There are no annual fees for life, including up to four supplementary cards.
Note that this is a premium credit card and requires a minimum annual income of S$120,000 to qualify.
UOB PRVI Miles Card
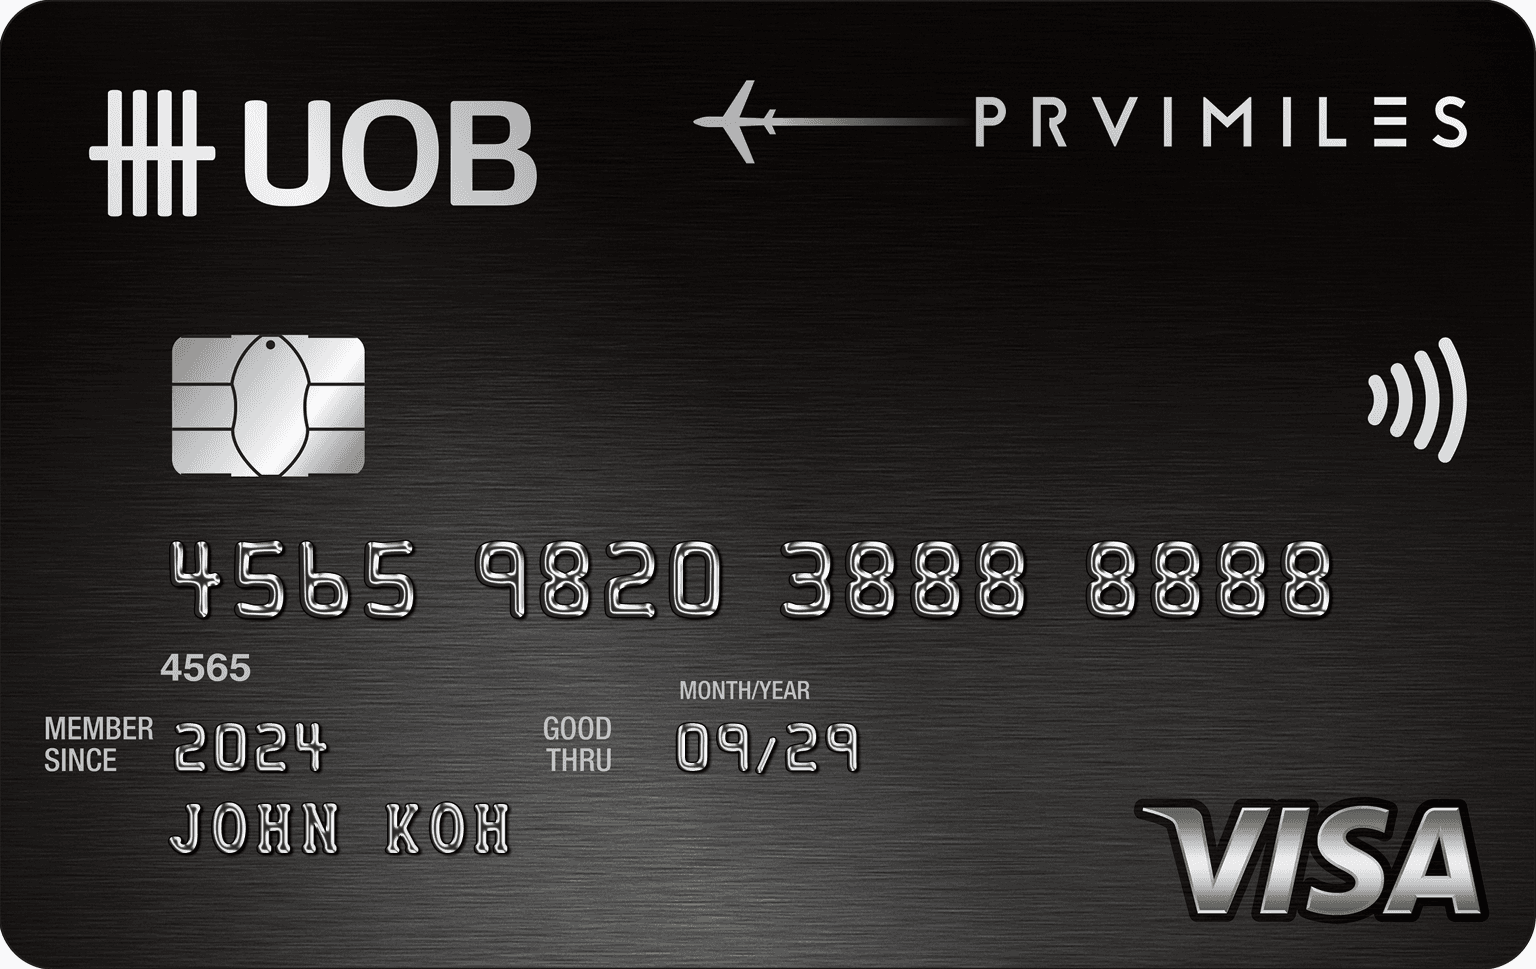
The UOB PRVI Miles Card stands out for its 1.4 mpd earn rate on local spend, among the highest for a general miles card. It also earns 2.4 mpd on overseas spend, rising to 3 mpd in Malaysia, Indonesia, Thailand and Vietnam.
Travel bookings are where this card really shines:
- Agoda: Hotel bookings made through the dedicated UOB PRVI Miles Agoda website earn up to 8 mpd.
- Expedia: Hotels, activities and car rentals booked through the UOB x Expedia page earn up to 8 mpd. Flights booked there earn 3 mpd.
Remember to book through UOB's dedicated links. Booking through the regular Agoda or Expedia site only earns the standard overseas rate.
There is no cap on how many miles you can earn, and no minimum spend to meet.
SingSaver x UOB Flash Deal ⚡
Get S$400 Cash, a Samsonite VOLANT Spinner, or an Ergotune Joobie when you are one of the first 5 eligible applicants at 10pm daily to sucessfully apply for selected UOB credit cards and make a min. spend of S$500 within the first 30 days of card approval. Remaining applicants will get S$80 Cash via PayNow. Promotion is valid for new-to-UOB credit cardmembers only. Valid till 31 October 2026. T&Cs apply.
Maybank Horizon Visa Signature Card
Maybank Horizon Visa Signature Card
This Maybank credit card offers an uncapped 2.8 mpd on foreign currency spend and air tickets, making it a great choice for your travel expenses.
The catch is that you'll need to spend at least S$800 in the same calendar month to unlock that rate. Miss it, and your foreign currency spend earns just 1.2 mpd. Maybank also occasionally boosts the rate to 3.2 mpd during peak travel periods.
The card provides complimentary travel insurance of up to S$1 million when you charge your travel fares in full to it. For complimentary lounge access, you'll need a single retail transaction of at least S$1,000 within the three months before your visit.
HSBC TravelOne Credit Card
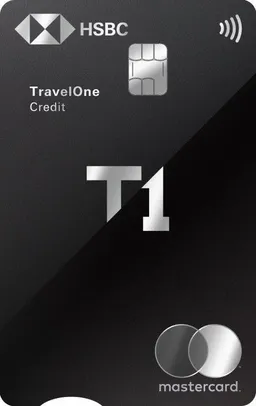
The HSBC TravelOne Credit Card offers an earn rate of 2.4 miles per dollar (mpd) for all foreign currency spends, as well as 1.2 mpd for local transactions.
But with the option to get up to five supplementary cards for free – and earn rewards as your family members spend on them – you’ll soon have more than enough air miles for your family holiday.
Another reason to choose this card for family travel is the customary free travel insurance coverage (up to S$100,000) that extends to family members travelling with you, instead of just being limited to the principal cardholder, as is the case with many other cards.
This card also has four complimentary airport lounge visits per annum, albeit only for the principal cardholder.
DBS Altitude Card
With 2.2 mpd for foreign spends (1.3 mpd for local transactions), the DBS Altitude Card lags a little behind other credit cards for overseas spending. However, it provides other ways to increase your air miles balance. For instance, Agoda bookings made on DBS Travel & Leisure Marketplace (TMP) will earn you 3 miles per dollar.
There are also other avenues for you to receive bonus air miles. You will automatically be awarded 10,000 miles when you pay your annual fee, which stands at S$194.90 at the time of writing. That translates to an unbeatable 51.3 mpd – too bad you can only take advantage of this once per year!
Best credit card for overseas transactions with no FCY fee: Trust Freedom Card
The seven credit cards above offer attractive cashback and air miles for travellers. But they all charge foreign currency transaction fees of around 3.25%.
If you'd rather not pay any foreign transaction fee at all, the Trust Freedom Card is a fuss-free alternative. It charges 0% FCY fees and converts foreign currency amounts into SGD at the prevailing Visa rate, with no extra markup.
Relaunched from the Trust Cashback Card in August 2026, it lets you choose a rewards mode: Unlimited Cashback, Bonus Cashback, Stockback or Miles. In Miles mode, you earn an uncapped 1.3 KrisFlyer miles or Max Miles per S$1 on both local and foreign currency spend.
That earn rate is lower than dedicated miles cards. But once you factor in the FCY fee you save, it's a strong fallback for large overseas purchases or after your other cards hit their bonus caps.
You should still watch out for DCC charges, explained below.
How to activate your credit card for overseas use
In Singapore, banks switch off some overseas card functions by default to protect you from fraud. Before you travel, check that your card is set up for overseas use.
- Open your bank's mobile app and go to your credit card's settings or card controls.
- Turn on overseas transactions. Some banks list separate toggles for in-store payments, online foreign currency purchases and magnetic stripe use.
- Enable overseas ATM withdrawals if you plan to take out cash. This is often a separate setting.
- Set the duration. Many banks let you activate overseas use for a set period, such as the length of your trip.
- Turn on transaction alerts so you're notified of every charge while you're away.
If you can't find these settings, call your bank's hotline before you fly. Save the bank's overseas hotline number, too, in case your card is lost or blocked while you're abroad.
Understanding credit card foreign currency fees
Credit cards offer attractive rewards for overseas spending, but you'll also pay extra fees on foreign transactions. Factor these in to see the real value you're getting.
Why is there a foreign currency fee when I use my credit card overseas?
When you pay in a foreign currency, your card network (Visa, Mastercard or American Express) converts the amount into SGD at its exchange rate. You're then charged a foreign currency transaction fee, usually around 3.25% in total. This is made up of a charge from the card network plus an admin fee from your bank.
See the following table for a summary. [VERIFY: rates per issuer]
| Card issuer | FCY admin fee |
|---|---|
| American Express | 3.25% |
| Citi | Visa/Mastercard: 3.25%, American Express: 3.3% |
| DBS/POSB | Visa/Mastercard: 3.25%, American Express: 3% |
| HSBC | 3.25% |
| Maybank | 3.25% |
| OCBC | 3.25% |
| Standard Chartered | 3.5% |
| Trust | 0% |
| UOB | 3.25% |
DCC: Why you should say no
When using your credit card overseas, you’ll need to watch out for another money trap that will cause you to spend more than necessary.
This is Dynamic Currency Conversion or DCC, and basically, it converts your foreign currency amount at the point of sale into SGD, presumably so it’s easier for you to gauge whether you’re getting a fair price.
The problem is, with DCC, the merchant is free to use any forex rate they choose, and this inadvertently turns out to be much higher than market rates as a way to fleece unsuspecting tourists.
There is also an additional 1% DCC service fee added to the converted amount, levied by the payment network providers.
DCC is optional, and tourists are free to choose whether they want to use DCC or not. But some unscrupulous vendors may foist DCC on you by not asking you beforehand, or claiming it’s required by law.
If you see your bill being presented in SGD instead of the currency of your host country, you’ll know they’re trying to charge you extra. Either request to pay in the local currency, or walk away and buy from another shop.
Incidentally, this also applies to online transactions. If the e-store you are buying from is registered as an overseas merchant, or processes payments through an overseas intermediary, you will be charged an additional 1% when paying in SGD
If you’re unsure, check with the online merchant whether payments are processed overseas. If indeed so, request to pay in the relevant foreign currency to avoid this extra fee.
Frequently Asked Questions (FAQ)
The best credit cards for overseas spending offer high miles, cashback or reward points on foreign currency transactions, enough to outweigh the FCY fee of around 3.25%. For miles, the HSBC TravelOne and UOB PRVI Miles cards earn up to 2.4 mpd. For cashback, the CIMB Visa Infinite Card offers unlimited cashback on overseas spend.
Look beyond earn rates to travel perks like complimentary travel insurance, airport lounge access and bonus miles on travel bookings. Cards like the HSBC TravelOne and CIMB Visa Infinite combine strong overseas rewards with these benefits.
The Trust Freedom Card charges no foreign transaction fees and converts at the prevailing Visa rate. Most other cards in Singapore charge between 3.25% and 3.5%.
Go to the card settings or card controls in your bank's mobile app. Turn on overseas transactions, and overseas ATM withdrawals if needed, then set the dates you'll be away. If you can't find the settings, call your bank before you travel.
Use a card with no FCY fees, such as the Trust Freedom Card, or a multi-currency card. Always decline DCC and pay in the local currency instead of SGD.
About the author
Afina Najib
Spending most of her young writer's phase working as a freelancer, Afina's written for various industries ranging from e-commerce, travel to health and finance. Her expertise lies in her ability to make complex subjects like finance easy to consume for everyday readers.
The information on this page is for educational and informational purposes only and should not be considered financial or investment advice. While we review and compare financial products to help you find the best options, we do not provide personalised recommendations or investment advisory services. Always do your own research or consult a licensed financial professional before making any financial decisions.