OCBC 365 Credit Card Review (2026): 6% Cashback on Everyday Spend from 1 Nov
Updated: 5 Oct 2026

Written bySingSaver Team
Team
⚡ Quick Answer
| Card | Card benefit | Annual Fee | Minimum Monthly Spend |
|---|---|---|---|
| 0.25 - 6 % cashback | S$196.20 | - |
Disclaimer: The information on this page is for general educational and informational purposes only and should not be considered financial or investment advice.
That makes it one of the strongest OCBC cashback credit cards for everyday family spending. The trade-off is that telco and utility bills, EV charging, streaming and (from April 2027) Watsons drop to 0.25%. In this OCBC 365 credit card review, we cover what you'll earn, the fees and interest rates, and whether the card still suits you after the change.
In this blog, you will learn more about one of OCBC's best credit cards for everyday spend.
What the OCBC 365 Credit Card can do for you
OCBC 365 credit card product summary (from 1 Nov 2026):
- Highest cashback rate: 6% on dining, groceries, land transport and petrol
- Minimum monthly spend: S$800 (single tier, down from two tiers of S$800 and S$1,600)
- Maximum cashback: S$160 a month (previously S$80 at S$800 spend)
- Annual income requirement: S$30,000 (Singaporeans/PRs), S$45,000 (foreigners)
- Annual fee: S$196.20 (first 2 years waived; after that, spend S$10,000 a year for a waiver)
| Pros ✅ | Cons ❌ |
|---|---|
| 6% cashback on dining (now including fast food), groceries, land transport and petrol from 1 Nov 2026 | You need S$800 in monthly spend; below that, everything earns 0.25% |
| The S$160 cap now unlocks at S$800 spend, not S$1,600 | Telco, utilities, EV charging and streaming drop to 0.25% from 1 Nov 2026 |
| No per-category cashback caps | Watsons drops from 3% to 0.25% from 1 Apr 2027 |
| Bonus rates cover in-store and online spend, locally and overseas | All other spend earns 0.25% |
| Two-year annual fee waiver | 3.25% foreign currency transaction fee |
OCBC 365 credit card cashback: before and after 1 Nov 2026
| Spend category | Until 31 Oct 2026 | From 1 Nov 2026 |
|---|---|---|
| Dining (fast food now included) | 5% | 6% |
| Groceries | 3% | 6% |
| Land transport (including SimplyGo) | 3% | 6% |
| Petrol | 6% | 6% |
| Telco, utilities, EV charging and streaming | 3% | 0.25% |
| Watsons | 3% | 3% until 31 Mar 2027, then 0.25% |
| Minimum monthly spend | S$800 or S$1,600 | S$800 |
| Monthly cashback cap | S$80 or S$160 | S$160 |
| Eligible spend below S$800 | 0.25% | 0.25% |
| Eligible advertising platform spend | Up to 1%, no cap or min spend | Up to 1%, no cap or min spend |
Benefits of the OCBC 365 Credit Card
#1: 6% cashback across four everyday categories
From 1 Nov 2026, the OCBC 365 credit card earns the same 6% rate across all its core categories:
- 6% cashback on local and overseas dining, including online food delivery and (new) fast food
- 6% cashback on groceries, including online grocery delivery (up from 3%)
- 6% cashback on land transport, including SimplyGo bus and MRT rides (up from 3%)
- 6% cashback on fuel at all petrol service stations, on top of station discounts
All other eligible spend earns 0.25%. To earn the bonus rates, you need to spend at least S$800 in a calendar month.
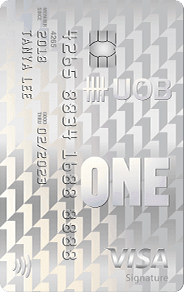
💡 Pro-tip: If you prefer one card for a broader mix of spending, the UOB One Card rewards consistent monthly spend across categories. See the comparison table below for current rates.
#2: Perfect for spending on daily necessities for the family
For most families, dining, groceries, transport and petrol make up most of the monthly budget. Once the new rates kick in, all four earn the same 6%.
That means S$12 back on a S$200 family dinner, compared with S$10 today. The same 6% applies to your weekly grocery run, including online groceries from RedMart and FairPrice Online.
Here's how a S$1,800 monthly family spend works out:
| Category | Monthly spend | Until 31 Oct 2026 | From 1 Nov 2026 |
|---|---|---|---|
| Dining | S$500 | S$25.00 (5%) | S$30.00 (6%) |
| Groceries | S$600 | S$18.00 (3%) | S$36.00 (6%) |
| Land transport | S$200 | S$6.00 (3%) | S$12.00 (6%) |
| Petrol | S$300 | S$18.00 (6%) | S$18.00 (6%) |
| Telco and utilities | S$200 | S$6.00 (3%) | S$0.50 (0.25%) |
| Total | S$1,800 | S$73.00 | S$96.50 |
In this example, you'd earn about S$23.50 more a month, even though bill payments drop to 0.25%.
#3: One simple spend tier
Until now, you had to choose between two tiers. S$800 in spend capped your cashback at S$80, and only S$1,600 unlocked the S$160 cap. From 1 Nov 2026, there's just one tier: spend S$800 and you can earn up to S$160.
At 6%, you'd need about S$2,667 a month in bonus categories before you hit the cap, so most cardholders will never reach it.
Recurring telco and electricity bills no longer earn bonus cashback. If you've been using this card for bills, consider moving them to one of the best cards for paying utility bills.
#4: Cashback cap is not limited to specific categories
The OCBC 365 credit card doesn't split its cap by category. You can earn up to the full S$160 from a single category if that's where most of your spend goes.
This makes it easier to earn more cashback in the categories you spend most on. It also works well if you combine several cashback cards.
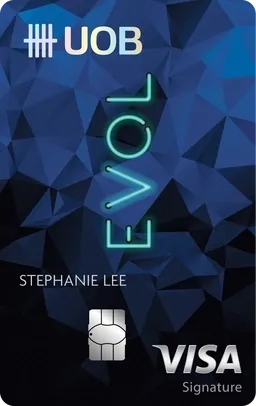
💡 Pro-tip: If most of your spend is online or through mobile contactless payments, the UOB EVOL Card is worth comparing. See the table below for current rates and caps.
Decision Guide
OCBC 365 credit card interest rate and fees
- Annual fee: S$196.20 (first two years waived). After that, spend S$10,000 in a card year for an automatic waiver.
- Interest on purchases: 27.78% p.a., with a minimum charge of S$2.50 a month
- Interest on cash advances: 28.92% p.a. on the amount withdrawn, compounded, with a minimum charge of S$2.50
- Cash advance fee: S$15 or 6% of the amount, whichever is higher
- Late payment charge: S$100 if the minimum payment isn't received by the due date
- Minimum monthly payment: 3% of the total balance or S$50, whichever is higher, plus any overdue amounts
- Foreign currency transaction fee: 3.25%
Pay your bill in full each month to avoid interest. The cashback you earn won't cover charges at these rates.
OCBC 365 credit card eligibility criteria
-
At least 21 years of age
-
Minimum annual income for Singapore citizens and PRs: S$30,000
-
Minimum annual income for Foreigners: S$45,000
For the card's full list of spend exclusions, refer here.
How to apply for an OCBC credit card
You can apply for the OCBC 365 Credit Card in a few minutes through SingSaver. Click Apply Now and complete the application on OCBC's site, where Singpass MyInfo can prefill most of your details. If you don't use MyInfo, prepare these documents:
- Front and back of your NRIC, passport or Employment Pass
- Salaried employees: your past 6 months' CPF statements (Singaporeans/PRs), or your latest Income Tax Notice of Assessment and latest computerised payslip
- Self-employed or commission earners: your latest Income Tax Notice of Assessment or latest 12 months' CPF statements
- Foreigners: your passport, Employment Pass, and latest computerised payslip plus Income Tax Notice of Assessment, or a company letter certifying your employment and salary
Before You Compare
Add up your dining, grocery, transport and petrol spend
These four categories earn 6% from 1 Nov 2026; most other spend earns 0.25%.
Make sure you'll hit S$800 every month
Missing the minimum drops all eligible spend that month to 0.25%.
Plan where your bills will go
Telco, utilities, EV charging and streaming earn only 0.25% from 1 Nov 2026.
Factor in the 3.25% FX Fee
Overseas spend earns bonus cashback but still incurs the foreign currency fee.
Check the fee waiver after year two
You'll need S$10,000 in annual spend to keep the annual fee waived.

Should you get the OCBC 365 Credit Card?
If you spend at least S$800 a month and most of it goes on dining, groceries, transport and petrol, the OCBC 365 is one of the most rewarding cashback credit cards after 1 Nov 2026. A flat 6% across all four categories, plus a S$160 cap at the lowest spend tier, works especially well for families who put household spending on one card.
It's a weaker fit if you mainly used it for bills, streaming or EV charging, since those drop to 0.25%. In that case, you could pair it with a bills-focused card. If you can't reliably hit S$800 a month, an uncapped flat-rate card like the OCBC INFINITY Cashback Card is the simpler choice.
About the author
SingSaver Team
At SingSaver, we make personal finance accessible with easy to understand personal finance reads, tools and money hacks that simplify all of life’s financial decisions for you.
The information on this page is for educational and informational purposes only and should not be considered financial or investment advice. While we review and compare financial products to help you find the best options, we do not provide personalised recommendations or investment advisory services. Always do your own research or consult a licensed financial professional before making any financial decisions.